Independent agency · Serving Texas since 1997214-351-4097
Insurance Plus
North Texas rental-property owners

Plano Landlord Rental Property Insurance

Compare Plano landlord insurance quotes for the home you now lease, with its roof history and ownership interests accurately recorded. A former residence or attached unit may need a different review from its previous insurance. Insurance Plus helps owners compare available terms and quote requirements.

An owner reviewing Plano landlord insurance with a property manager outside a rental home

Payment & billing options

Methods and installment plans vary by carrier. A quote request does not take payment or bind coverage.

Plano rental property insurance for the building you own

An established house converted from personal use needs a current rental description even when the owner keeps the same mortgage and mailing address. Provide the lease arrangement, owner-retained property and any changes in management before comparing proposals.

For Plano rental property insurance, provide the building’s year, size, construction and actual unit arrangement. List ownership and mortgage interests rather than carrying forward a prior owner’s assumptions.

An attached unit or home with shared facilities needs a review of association responsibilities. Obtain the applicable documents and actual master-policy information rather than assuming a neighborhood’s maintenance rules establish the insured building.

Keep the property description current through a purchase, repair or tenant change. Ask which inspection records and completed-work evidence the proposed market needs; an application should describe the premises as they stand today.

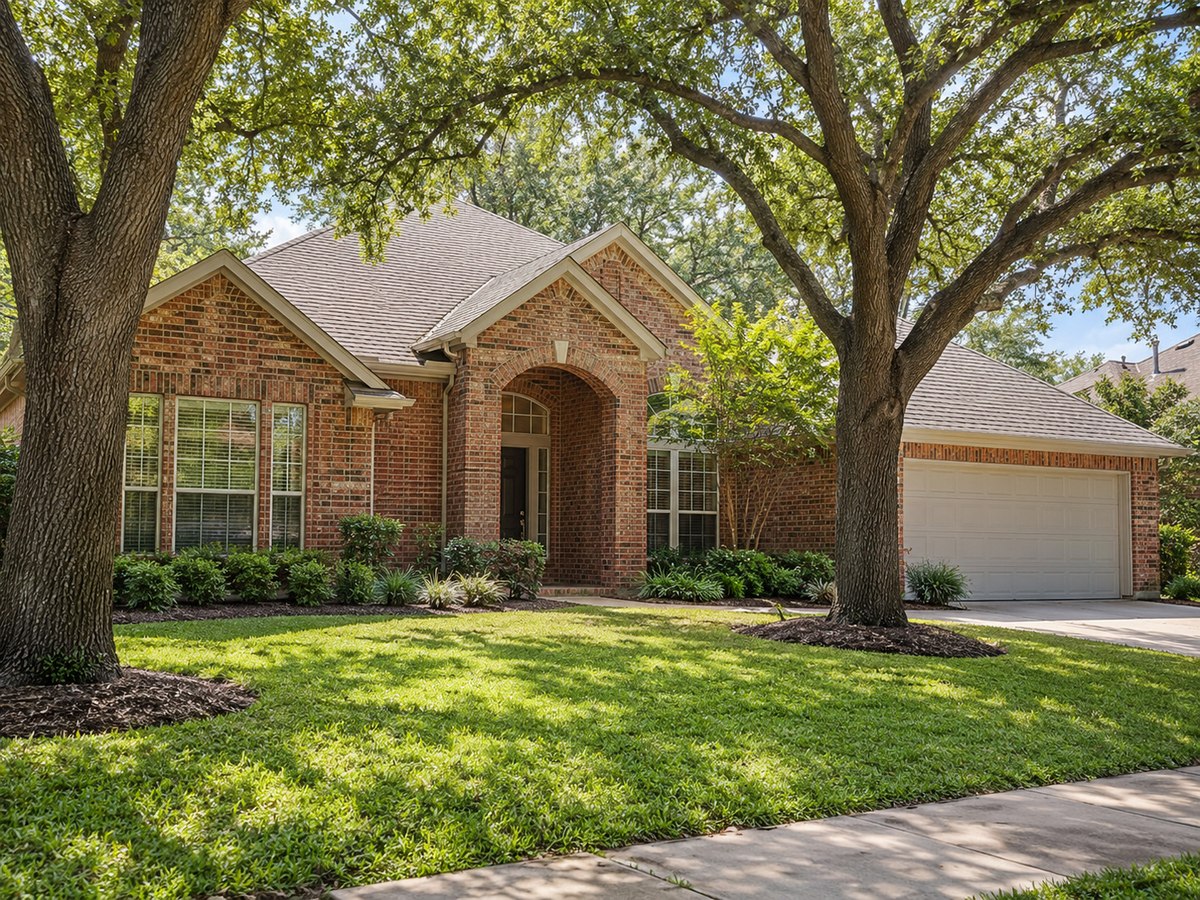
A maintained rental building illustrating Plano rental property insurance considerations
Describe the actual structure and leased units. Property imagery is illustrative, not a specific listing.

Keep the rental arrangement and the maintenance records current

A property owner reviewing shared-roof responsibilities outside an attached rental

Attached units and association responsibilities

For an attached home, distinguish what the association maintains from what its insurance actually covers. Identify interior improvements, fixtures and owner-owned appliances. A common roof does not automatically answer the owner’s liability or rent-interruption questions.

Keep Plano rental property insurance aligned with occupancy and ownership changes. Report the current arrangement before assuming the original terms remain appropriate.

If a former home is furnished for the next household, inventory the owner’s property before proposing limits. Personal possessions left in a locked room, appliances supplied to occupants and the tenant’s belongings are not interchangeable categories.

Report a change from an annual household lease to short stays or room rentals. The building can look unchanged while its use changes materially. Keep the current agreement and management responsibilities available for review.
An owner and contractor documenting completed repairs between tenants

Separate completed repairs from pending work

When a former home becomes a rental, record what remains on site and which repairs are complete. Keep owner storage and supplied appliances distinct from the tenant’s property. Update use before relying on the old declarations.

Roof and system invoices should show the work actually done, not merely a listing description. A modern kitchen may coexist with an older roof or unresolved electrical recommendation. Supply both sides of that condition record.

Report the interval between moving out and the new household taking occupancy, including utilities and work. A planned short gap should be updated if repairs or leasing take longer.

Read the vacant rental-property guide →

When comparing proposals, ask about any required inspections or repairs and whether relevant ordinance-or-law protection is available. Confirm outstanding items before relying on the proposed effective date.

Hail, roof history and the owner’s retained share

A North Texas roof comparison should begin with the roof actually on the building: installation date, material, repair history and unresolved inspection findings. A recent interior renovation is useful information, but it does not answer roof-specific underwriting questions.

Read any depreciation, payment schedule, cosmetic limitation or roof endorsement with the deductible. Ask how a percentage is calculated and whether settlement changes when replacement conditions have not been met. Building valuation and roof settlement need not be identical.

Plano provides floodplain and drainage-easement resources. Investigate the individual parcel and proposed work rather than inferring risk from a quiet subdivision or a previous flood-free lease. Rising water calls for a separate coverage discussion from hail or a plumbing leak.

A rental owner and contractor checking a roof-repair record beneath mature shade trees
Illustrative property review; the photograph does not document a particular weather loss.

Use an official address resource

The local flood, drainage or weather resource can help organize questions about the premises. Check the specific site and available records; do not infer an individual property’s risk or eligibility from a citywide description. Mapping and prevention information do not replace the wording of a proposed insurance contract.

Owner protection beyond the dwelling limit

Identify the premises and insured owner

Review the owner name, entity and premises liability limit. Describe features such as shared stairs, parking areas, a pool or a separately occupied structure. A management agreement does not itself establish which parties the insurance treats as insureds.

Keep maintenance responsibilities and tenant reporting clear. An owner policy and a tenant policy address different interests, and neither replaces routine care. Compare the actual liability terms and exclusions rather than assuming every injury or dispute is protected.

Keep different water concerns separate

Flood, plumbing discharge, drain backup and rain entry can be governed by different provisions. Describe the concern and ask how the proposed wording treats it. A single water-related limit is not a reason to assume that every kind of water damage is insured.

Compare separate flood protection where appropriate, including the property insured and effective date. Ask which available endorsements address other relevant concerns. A building’s location and maintenance history support the discussion but do not guarantee a claim outcome.

Landlord insurance for Plano rentals: review your options

Have building size, construction, roof material, update dates and current occupancy ready. Supply the address and ownership before comparing proposed limits.

Explain prior wind, water, fire or liability losses and the repairs completed afterward. Disclose a lapse or nonrenewal so the agency can review the current situation accurately.

Insurance Plus helps owners review Plano landlord insurance for eligible residential rentals. Insurance Plus has served Texas since 1997 and can explain available proposals and required information.

Same-day markets are available for eligible rentals, subject to underwriting approval and binding requirements. A form requests a review; it does not issue a policy. Confirm approval, agreed terms, effective dates and required payment before relying on coverage.

A property owner comparing building records and proposed coverage with an agency representative
Organized building, occupancy and ownership records support a clearer proposal comparison.

Converting a former residence without carrying over assumptions

A common planning situation is an owner retaining a house after moving. Tell the agency when owner occupancy ends, when the lease begins and whether work or an empty interval comes between them. Do not assume a homeowners renewal automatically accepts the new use.

Review the ownership name, lender and property retained on site. A family member collecting rent may not have the same role as a professional manager, and neither relationship establishes automatic insured status. Provide the actual arrangement.

Compare the building description and roof terms with the current rental facts. The purpose is to select suitable available protection, not simply reproduce the former premium with a different mailing address.

Nearby cities and communities

We also help rental-property owners in these nearby communities.

Questions before choosing coverage

Can I keep the old policy after moving out?

Tell the agency about the change before assuming it is accepted. Owner occupancy, tenant use and vacancy are different facts. The existing declarations alone do not confirm the appropriate program for the new arrangement.

Does a new interior establish replacement-cost roof coverage?

No. Roof settlement follows the actual contract and endorsements. Review installation records, depreciation or schedules and the deductible independently of interior updates and the dwelling’s valuation.

Does the purchase price establish the building limit?

No. Market value, the loan balance and reconstruction cost measure different things. Review an appropriate rebuilding estimate and the actual valuation and settlement provisions proposed for the structure.

Can roof settlement differ from the building’s valuation?

Yes. Read the actual roof endorsements, any depreciation or payment schedule, deductible and replacement-cost conditions separately. A broad dwelling description does not establish identical treatment for the roof.

What should I prepare when asking for assistance?

Call 214-351-4097 with the property’s current use, unit count and coverage questions. Keep the current declarations page and recent roof or repair records available for review.

Is same-day coverage available for every application?

Same-day markets are available for eligible rentals, subject to underwriting approval and binding requirements. A quote request does not itself issue coverage. Confirm agreed terms, effective dates and any required payment before relying on a policy.

Review the rental you own

Call 214-351-4097 or choose the appropriate quote form.

Quote · 1–4 unitsQuote · 5+ units