Home Coverage
May help repair or replace the mobile or manufactured home after a covered loss, subject to policy terms.

Compare coverage for mobile homes and manufactured homes across Texas, from established communities to private rural acreage. Review home protection, belongings, liability, storm deductibles and quote options with our Dallas-based independent agency. For owners comparing Texas mobile home insurance, we explain the choices without assuming every property qualifies for the same form.
Major credit cards and EFT/ACH may be accepted, depending on provider eligibility and payment plan.
Availability, billing plans, and down payments vary by provider.
Mobile and manufactured homes can need different coverage than a standard site-built house. Age, location, occupancy, tie-downs, roof condition, additions, and ownership details may all affect how the home is reviewed. Mobile home insurance in Texas should reflect the actual construction and occupancy.
Use this overview for mobile-home coverage, or choose the dedicated manufactured-home resource when your home was built to the federal HUD Code. True modular or industrialized homes are a separate construction category in Texas, so we route those owners to a dedicated modular-home insurance page.
Share your property details online or call Insurance Plus if you want help reviewing what may be needed before your quote can be completed.
Request Mobile Home QuoteLocal agency support • Property coverage options
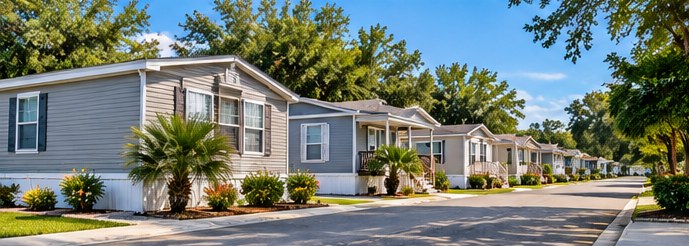
Illustrative image; coverage depends on property and policy terms.
A home located in a mobile home community can have different insurance considerations from a home on privately owned land. Tell us whether you own the home, lease the lot, and have additions such as a porch, deck, carport or storage shed. The park’s requirements do not automatically replace the need to insure your home and personal property.
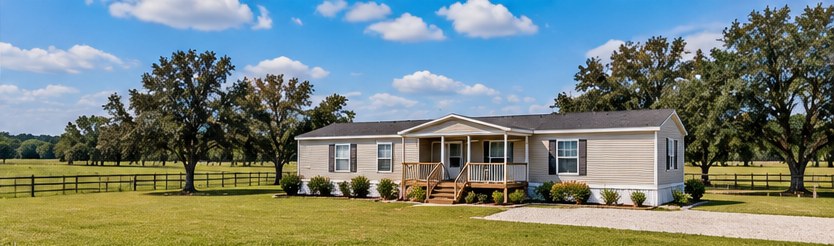
Illustrative image; coverage depends on property and policy terms.
A mobile home on a one- to three-acre private rural lot may face different exposures, including distance to a responding fire department, access roads, tree hazards and detached buildings. The insurance on the home is distinct from insuring the land itself; acreage and outbuildings should be disclosed for underwriting.
Illustrative image; coverage depends on property and policy terms.
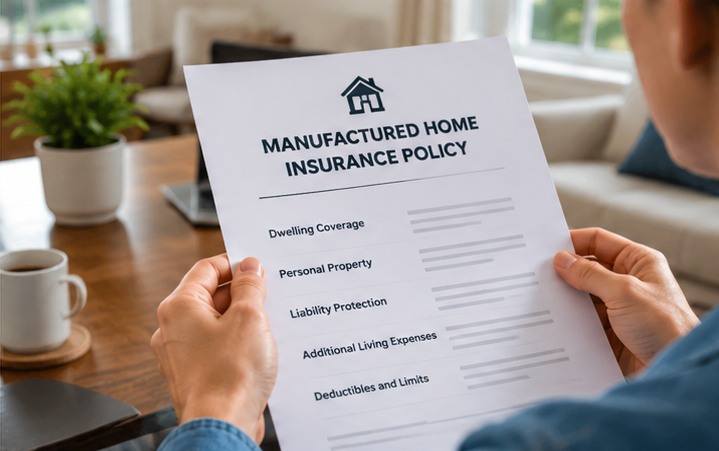
A home policy may provide coverage for furniture, appliances, clothing and electronics after a covered loss. Check the personal property limit, deductible and whether the policy settles losses on a replacement-cost or actual-cash-value basis. Additional living expenses may be available when a covered loss makes the home uninhabitable.
Mobile home coverage can include several important parts. Coverage availability, limits, deductibles, endorsements, and eligibility vary by provider and property details.
May help repair or replace the mobile or manufactured home after a covered loss, subject to policy terms.
May help cover furniture, clothing, electronics, and other belongings damaged by a covered cause of loss.
May help protect against covered claims involving injury or property damage to others.
Depending on the policy, decks, porches, sheds, skirting, or similar property may need review.
May help with additional living expenses if a covered loss makes the home temporarily unlivable.
Deductibles, down payments, billing plans, roof provisions, and payment options should be reviewed before choosing coverage.
Flooding from rising water is generally not covered by standard property insurance. Ask about separate flood coverage where appropriate. Fire protection distance, prior losses and the home’s condition can also influence available options.
Weather is also important in Texas. Wind, hail, severe storms, fire, water concerns, and deductible choices should be reviewed carefully. The goal is to understand what is covered, what is limited, and what information the provider may need.
A mobile home quote may depend on the home’s age, location, size, serial or VIN information, roof condition, prior claims, occupancy, selected limits, deductible choices, and whether the home has additions or detached structures.
Accurate property information helps prevent delays. Before requesting a quote, it can help to know whether the home is owner-occupied, rented to someone else, located in a park, placed on private land, or used seasonally.
A standard homeowners policy is usually built around a site-built owner-occupied house. Mobile and manufactured homes often need a specialized policy form. If the property is rented to tenants, a landlord policy may be more appropriate than owner-occupied coverage.
Tyr cverage review should include the structure, occupancy, location, and payment preferences. If you own a site-built house, visit our homeowners insurance page. If the property is rented, review landlord coverage.
The right coverage route depends on how the home was built, its age, occupancy, and location. Use these resources to review the situation that best matches your property.
Review coverage considerations for HUD-code manufactured homes, including structure, belongings, liability, and property details.
See how age, updates, roof condition, tie-downs, and overall property condition may affect insurance options.
Modular homes are a separate factory-built category in Texas. Review insurance for modular or industrialized homes built to site-built housing codes.
Review wind and hail options when coastal exposure, roof terms, or windstorm eligibility requires additional attention.
Mobile-home policies may value covered damage using replacement cost or actual cash value (ACV), subject to eligibility, policy language and limits. ACV generally accounts for depreciation, so an older home may receive a smaller claim payment than the cost of a new replacement. Review settlement terms before choosing a policy.
Compare the main deductible with any separate wind or hail deductible. Confirm whether attached porches, decks, awnings and detached structures are included, limited or require an endorsement. Insurance Plus serves mobile home owners throughout Texas.
Common questions from Texas mobile and manufactured home owners reviewing coverage.
Your home insurance should cover the manufactured home, personal belongings, liability, additional living expenses, and certain attached or detached structures after a covered loss.
No. Mobile and manufactured homes may require specialized coverage based on the structure type, age, location, ownership, and occupancy.
Age, location, construction type, tie-downs, roof condition, occupancy, prior claims, coverage limits, deductibles, and payment options may affect the quote.
A mobile home rented to tenants may need landlord or rental property coverage instead of owner-occupied mobile home coverage.
Payment options vary by provider, but major credit cards and EFT or ACH payment options may be available when eligible.
Coverage varies by insurer, location and policy. Wind and hail may be included, limited, excluded or subject to a separate deductible. Review the declarations and exclusions before buying.
Flooding from rising water is generally excluded from standard property policies. Separate flood insurance may be available, subject to eligibility and policy terms.
Both situations may be insurable. A carrier may ask whether you own or rent the lot, whether the home is permanently installed, and about additions, occupancy and fire protection.
Mobile homes built before June 15, 1976 predate the federal HUD construction standards. Homes built to the HUD Code after that date are generally classified as manufactured homes. Insurance eligibility depends on the specific home and carrier.
Request a mobile home quote online or call Insurance Plus for help with property coverage questions.
Our Foremost program information explains questions to review when considering an available specialty property program. Eligibility depends on the property and insurer.