Dwelling and structures
Set building limits using a realistic reconstruction estimate. Market value, the purchase price and the mortgage balance may differ from the cost to rebuild. Identify detached structures separately.

Compare Austin landlord insurance quotes around your building, rental use and income needs. Review coverage and deductibles with an independent agency before choosing a policy. Insurance Plus serves owners across Central Texas; choose the quote card for your building size.
Payment & billing options
Methods and installment plans vary by carrier. A quote request does not take payment or bind coverage.
A former residence converted to a long-term rental needs a different review from a newly purchased duplex. Tell the agency who owns the building, who occupies it and whether any part remains owner-occupied.
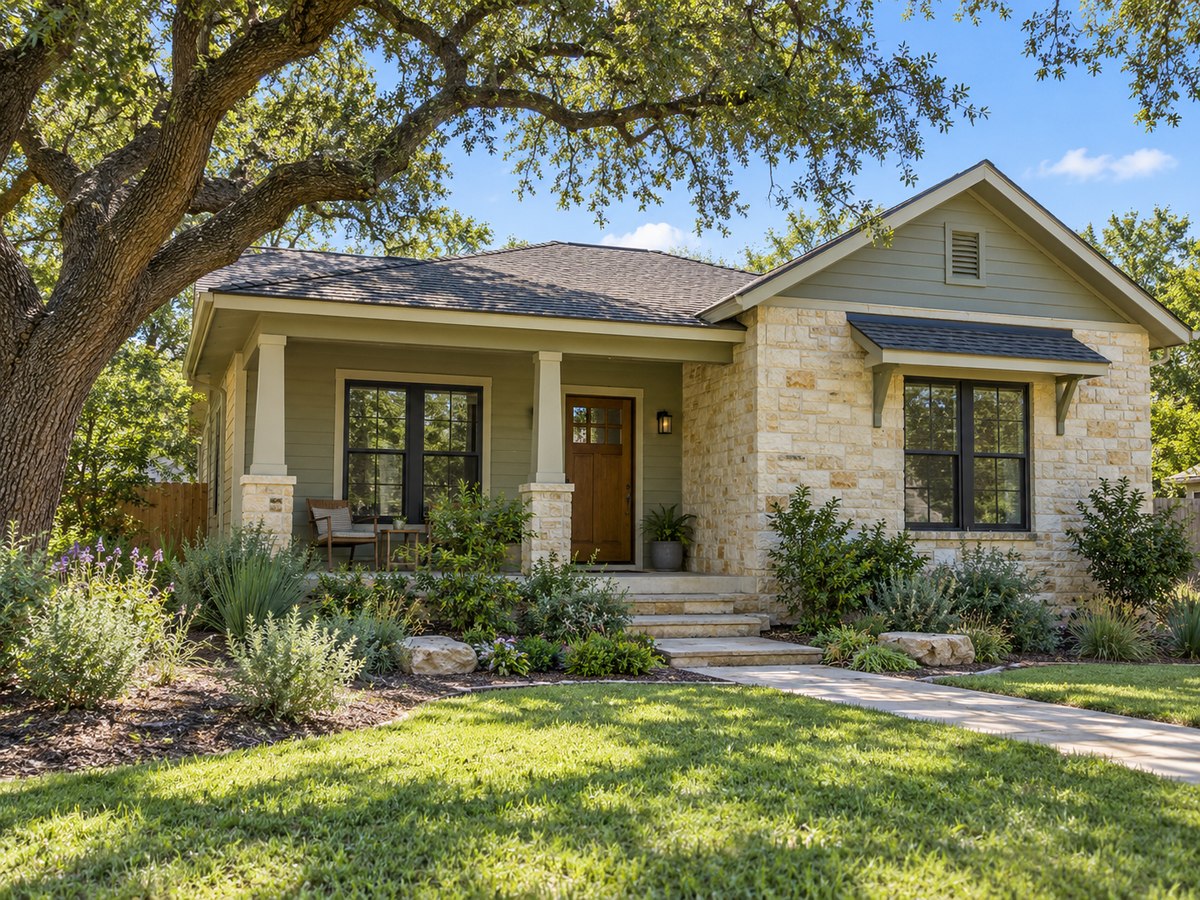
When comparing Austin rental property insurance, include the main dwelling, separately rented accessory units and any owner-owned appliances or furnishings. A guest house or converted garage should not be left off the application.
From older central-city homes to suburban fourplexes, building age, roof condition and remodeling history matter. Share updates to wiring, plumbing and heating systems rather than relying only on the year built.
North, South and East Austin addresses can involve different construction and rental arrangements. We review the individual property rather than assuming every rental near MoPac or I-35 belongs in the same program.
If you recently purchased the home, keep inspection findings and repair invoices. An updated roof or electrical system should be documented, while unfinished work needs to be disclosed before coverage is arranged.
Available protection depends on the carrier, policy form and selected endorsements. Check what is actually included.
Set building limits using a realistic reconstruction estimate. Market value, the purchase price and the mortgage balance may differ from the cost to rebuild. Identify detached structures separately.
Review protection for eligible bodily injury or property damage claims involving the premises. Disclose pools, stairs, shared areas and management arrangements so the policy matches the exposure.
Eligible coverage may replace rental income when a covered loss makes the building uninhabitable. Confirm limits and repair periods; ordinary nonpayment or an empty unit is not the same trigger.
Ask about appliances, furnishings and maintenance equipment kept at the rental. The owner's policy generally does not insure a tenant's belongings; tenants should review their own protection.
Roof age, construction, system updates, loss history and occupancy can affect eligibility and pricing. A low premium needs to be considered alongside exclusions, inspection requirements and the amount you would pay after damage.
Compare replacement cost with actual cash value, including any separate roof provisions. Check whether wind and hail use a flat deductible or a percentage of the insured value. A percentage can mean a substantial out-of-pocket expense.
Discuss sudden water damage, freeze precautions, water backup and any available ordinance or law protection. Maintenance, wear and tear and long-term leaks should not be assumed covered.
Ask what documentation the insurer needs after a loss. Current exterior photographs, a record of repairs and a copy of the lease can help explain the building’s condition and use.
Flood requires a separate review. The City’s FloodPro mapping resources can help owners investigate a particular address. Ask about flood protection rather than treating a standard dwelling policy as protection against rising water.
DP1, DP2 and DP3 labels help organize a conversation, but the form, endorsements and exclusions control the coverage. Do not judge protection by the label alone.
A basic form typically identifies the events it covers. Ask which causes of loss are listed, how the building is valued and whether vandalism or other desired protection needs an endorsement.
Explore DP1 coverage →A broader named-peril form may address more events than a basic option. Compare the particular contract, deductible and settlement provisions rather than assuming every carrier uses identical wording.
Explore DP2 coverage →A special dwelling form generally covers the building on an open-peril basis, subject to exclusions. Roof valuation, vacancy restrictions and optional endorsements still deserve a careful review before purchase.
Explore DP3 coverage →
A turnover gap is different from an extended vacancy or a building with open walls and disconnected utilities. Notify the agency before tenants leave, major work begins or the property is prepared for sale.
Explain whether a detached unit is rented separately and whether leases are long-term, student-oriented or short-term. Guest stays and furnished vacation use can require a different program from a traditional lease.
Keep Austin rental property insurance aligned with the current use, not just the occupancy recorded when you first bought the building. Keep dated photos with your records.
Review vacant rental-dwelling coverage →
List the individual, partnership or company that owns each location, along with mortgage information and property-manager responsibilities. Tell us if ownership is changing before closing or renewal.
For a portfolio, compare building limits, deductibles and renewal dates across locations. Several properties do not automatically belong in one policy; carrier rules and building characteristics still matter.
Buildings with five or more units use our apartment form. Have the unit count, building schedule, occupancy and rental-income information ready for the commercial review.
Request a multifamily quote →Gather the property address, year built, square footage, roof age, major updates and prior claims. Include the unit count, occupancy, current carrier, renewal date and requested coverage effective date.
Have your current declarations and any inspection or renovation records nearby. Tell us about unrepaired damage or a recent cancellation so the submission reflects the building as it stands today.
For a purchase, share the closing date and lender’s requirements early. For a renewal, compare matching building values and liability limits so a lower premium is not simply the result of reduced protection.
Insurance Plus can help you review Austin landlord insurance options for an eligible residential rental. Insurance Plus is an independent Texas agency serving property owners since 1997.
Compare available terms before authorizing coverage. A request is not a binder; effective dates, approval and any required payment must be confirmed with the agency or carrier.
Request a Residential Quote
Review occupancy changes before replacing an owner-occupied policy.
Read the guide →Understand covered interruptions, limits and repair-period questions.
Read the guide →Consider owner responsibilities and protection for eligible claims.
Read the guide →For nearby communities in the Austin area, choose the page that matches your rental.
Do not assume an owner-occupied policy fits a tenant-occupied home. Tell the agency before the use changes so the building, liability and rental-income needs can be reviewed.
Generally, this coverage responds to eligible income loss after a covered event makes the property uninhabitable. Ordinary nonpayment, eviction and routine vacancy are not the same trigger. Check the actual policy limits and conditions.
Eligibility depends on the carrier, building condition, ownership and occupancy. Disclose every rented unit, including a detached guest house or converted garage, so the application accurately describes the risk.
Contact the agency before work or vacancy begins. The existing policy may restrict coverage or require a different form. Explain the scope of work, utilities, expected completion date and plans for the next tenant.
Use the residential property form for one to four units. Use the apartment form for five or more units; the hero cards distinguish smaller multifamily properties from larger apartment buildings.
No. A quote request supplies information for review. Coverage depends on approval, agreed terms, the confirmed effective date and any required payment or binding instructions.
Choose the form for your building size. Insurance Plus serves owners throughout Texas: 214-351-4097.