Independent agency · Serving Texas since 1997214-351-4097
Insurance Plus
Coastal Bend rental-property owners

Corpus Christi Landlord Rental Property Insurance

Compare Corpus Christi landlord insurance quotes around your building, coastal exposure and rental use. Review wind, water, liability and income-protection terms before selecting coverage. Insurance Plus serves owners throughout Texas; choose the quote option for your building size.

An owner and property manager reviewing Corpus Christi landlord insurance outside a coastal rental home

Payment & billing options

Methods and installment plans vary by carrier. A quote request does not take payment or bind coverage.

Coastal protection starts with separate questions

Review windstorm and flood arrangements first

The building policy, wind coverage and flood protection may not be one contract. Identify each exposure and compare the actual terms rather than relying on a single premium.

A rental owner checking storm shutters and securing a coastal porch before severe weather

Wind, openings and roof documentation

Ask whether wind and hail are included, excluded or arranged separately. Read hurricane or named-storm deductibles and confirm whether your share is a flat amount or a percentage of the stated insured value.

Nueces County is part of the designated coastal windstorm area. For a TWIA placement, ask which inspections and compliance records apply to the structure, roof replacement or later improvements; a certificate does not by itself guarantee coverage.

Prepare roof dates, opening-protection details and repair invoices. Distinguish permanent work from temporary storm measures before the application is reviewed.

Review windstorm coverage options →
Shallow rainwater beside a street curb and storm drain near a coastal rental home

Rising water and the specific address

Standard rental-dwelling policies generally exclude flood. Evaluate separate protection for rising water and storm-surge exposure rather than assuming wind or plumbing coverage handles those losses.

Use the City’s flood maps and property-risk resources alongside elevation, drainage and loss-history information. Lower mapped risk does not mean the possibility of flooding is eliminated.

Compare flood limits, deductibles, insured property and any waiting period. The rainfall image is illustrative and does not show a documented local event, insured loss or particular property’s risk classification.

Explore separate flood protection →

Plan inspections before roof or structural work

Ask your contractor which windstorm inspections and compliance records the proposed work requires before construction begins. TDI distinguishes a WPI-8 certificate for qualifying ongoing construction from a WPI-8-E for qualifying completed construction. Roof replacement and major repairs may require inspection and certification for TWIA eligibility; requirements and exceptions depend on the work.

Keep certificates with the property records and explain additions or later alterations. If work is already finished, ask about the appropriate completed-construction review rather than assuming a receipt is sufficient. An inspection certificate is a building-compliance record, not a policy or guarantee of acceptance.

Check TDI windstorm inspection guidance →
One city, different building and occupancy needs

Corpus Christi rental property insurance for your building

A long-term inland rental, a coastal condo and a furnished island property can require different submissions. Describe what you own, who occupies it and every structure or unit used by a tenant.

When comparing Corpus Christi rental property insurance, identify detached garages, separately rented living units and owner-owned appliances or furnishings. Explain kitchens, utilities and tenant access rather than assuming every improvement falls within the main dwelling limit.

Flour Bluff, Calallen, Annaville, the Bay Area and North Padre Island include properties with different construction and update histories. The address, roof condition, elevation and actual use should drive the review—not a neighborhood label alone.

For a condominium or townhome, supply relevant association coverage information. Clarify your responsibility for interior finishes, fixtures and other property before selecting limits or comparing proposals.

Building values should reflect an appropriate reconstruction estimate. Market value and the remaining loan balance may not represent the cost of a covered rebuild.

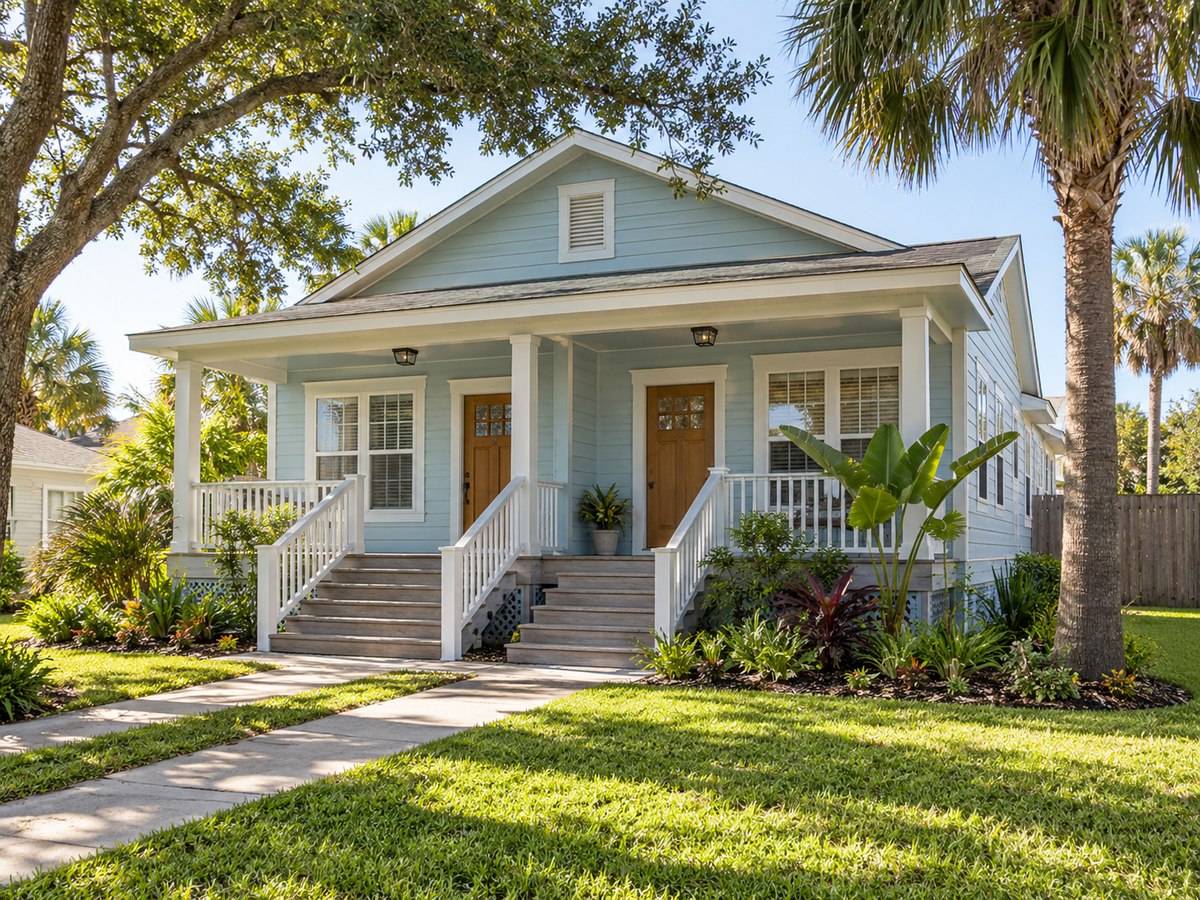
A coastal duplex illustrating Corpus Christi rental property insurance needs for separate leased units
Identify every leased unit and the owner’s responsibilities. Property imagery is illustrative, not a specific local listing.
Rental use affects the market review

Student housing, furnished rentals and seasonal occupancy

Tell the agency how the building is used today and whether that use changes during the year.

A property owner reviewing lease and occupancy details with two adult college students

Students and shared-house arrangements

Owners renting to students near Texas A&M University–Corpus Christi should describe the lease and household arrangement. One household lease, separate room leases, unrelated adults and an owner-occupied room are different application details.

Keep Corpus Christi rental property insurance aligned with occupancy changes and furnishings you supply. Do not submit a shared-house arrangement as a different use simply because the exterior resembles a standard home.

Tenants’ belongings and personal liability generally require their own coverage.

Review a change from home to rental →
A rental owner recording furnished coastal townhome contents on a tablet

Furnished stays and mixed personal use

A long-term lease is different from frequent guest turnover, seasonal vacancy or a vacation rental that the owner also uses. Describe booking duration, occupancy gaps, management and the property you provide for guests.

Do not assume a traditional rental-dwelling form or a booking platform replaces a review of short-term use. Ask which market and policy terms fit the actual arrangement, including the periods between bookings.

Keep a furnishings inventory and update the agency before changing the rental pattern.

Explore rental-property coverage →
The condition of the building still matters

Maintenance, repairs and larger property schedules

Coastal exposure does not replace the need to document building condition, responsibilities and current occupancy.

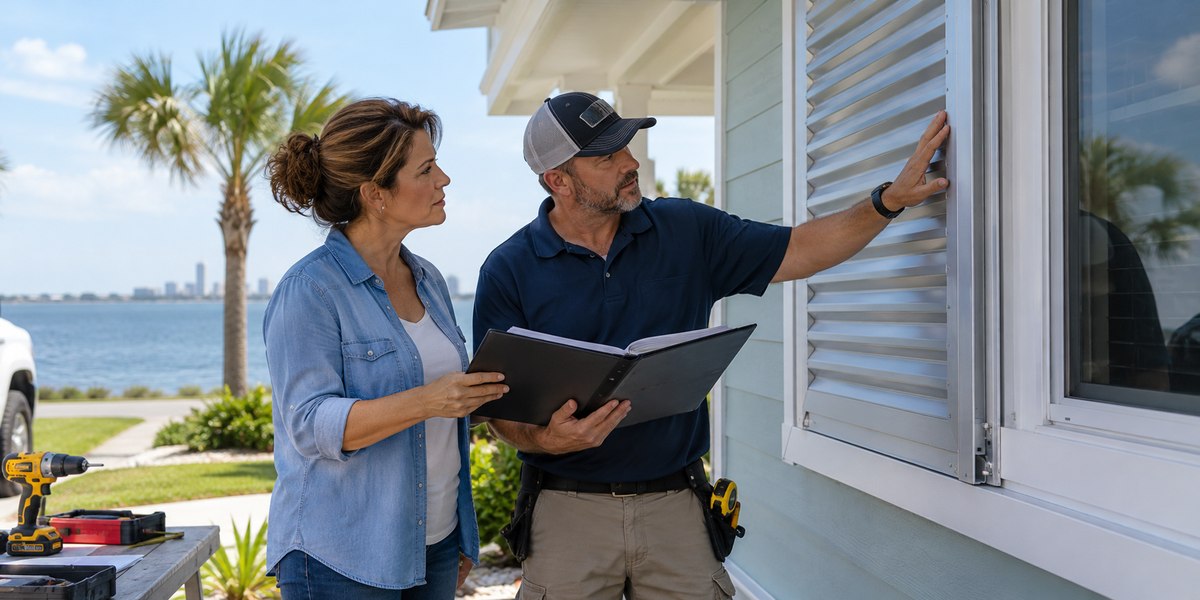
An owner and contractor checking exterior window protection and repair records

Keep completed work and pending repairs separate

Collect roof, exterior, window and opening-protection records. Explain unresolved damage, temporary repairs and any changes made after an earlier storm instead of assuming a closed claim establishes the current condition.

Tell the agency about extended vacancy, disconnected utilities, open walls or major renovations. Report the work schedule and when tenants are expected to return; maintenance and wear are not automatically covered losses.

Ask about relevant ordinance-or-law protection when comparing covered repair terms.

Read the vacant rental-property guide →
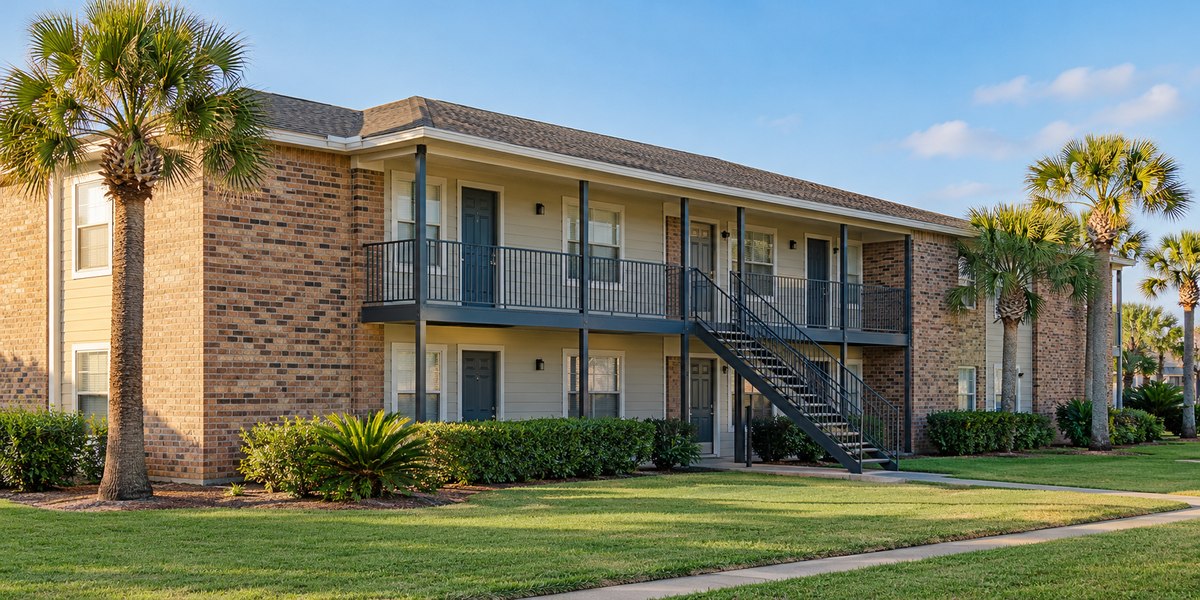
A modest coastal apartment building with shared stairs and tenant walkways

Review each building in a portfolio

Five or more units use our apartment form. Prepare building schedules, occupancy, rent-roll information, management responsibilities and prior losses for commercial property and liability review.

For multiple locations, list dwelling limits, roof terms, storm deductibles and separate wind or flood policies by address. Properties considered together may still require different carriers, contracts or renewal arrangements.

Identify ownership entities and mortgages so the submission describes each insured interest correctly.

Request a multifamily quote →

Eligible loss-of-rents protection may address income interruption when a covered loss makes the rental uninhabitable. Review the triggering event, limits and covered repair period. Ordinary nonpayment, eviction or a routine vacant period is a different exposure.

When wind, flood and the building are covered under separate contracts, ask which policy provides any rental-income benefit and how its covered cause of loss applies. Do not assume an income limit on one declarations page extends to every storm-related interruption. Compare the waiting period, documentation and maximum payment duration as well as the dollar limit.

Gather the records, then compare the terms

Landlord insurance for Corpus Christi rentals: review your options

Prepare the address, year built, construction type, unit count, square footage and requested effective date. Include roof details, system updates, current occupancy and ownership.

Have declarations, inspection findings and repair invoices nearby. Disclose wind, flood, water, fire and liability losses, plus cancellations, nonrenewals or gaps in coverage.

Insurance Plus helps owners review Corpus Christi landlord insurance for eligible residential rentals. Insurance Plus has served Texas since 1997 and can explain available proposals and required information.

  • Compare equivalent building and liability limits.
  • Check roof terms and storm deductibles.
  • Review separate flood and rental-income protection.
  • Confirm inspection and binding requirements.
Request a Residential Quote
A rental owner and insurance adviser reviewing roof records and building documents
Organized building, ownership and storm-history records help the agency review available options.

Read the coverage behind the form label

Compare DP1, DP2 and DP3 options using actual wording and endorsements. Review dwelling valuation, owner-owned property, premises liability, exclusions and settlement conditions. A tenant’s policy does not replace the owner’s property protection or maintenance responsibilities.

A request does not bind coverage or guarantee immediate issuance. Confirm approval, effective dates, binding instructions and any required payment before relying on a policy.

Review storm-season timing before a warning

Begin the coverage review before a storm threatens the coast. TWIA policy moratorium rules can restrict issuing new coverage or increasing existing protection during specified hurricane conditions. An application or quote request does not override those restrictions.

Ask about the proposed effective date, outstanding inspection items and when each separate contract can actually be bound. Flood waiting periods may also affect planning. Keep current declarations, emergency contacts and building records accessible so a last-minute search for documents does not delay a review.

Review TWIA’s policy moratorium information →

Nearby cities and communities

We also help rental-property owners in these nearby Coastal Bend communities.

PortlandService area
RobstownService area
InglesideService area
Aransas PassService area
RockportService area
OdemService area
Port AransasService area
TaftService area

Questions before arranging coverage

Does a building policy automatically cover wind and flood?

No. Read the specific policy and endorsements. Wind may be included or arranged separately, and standard dwelling policies generally exclude flood. Review each contract, deductible and effective date with the agency.

What coastal inspection records should I provide?

Provide available windstorm compliance certificates, roof dates, inspection reports and repair invoices. Explain later additions or alterations. The records needed depend on the property, proposed work and insurer; a certificate alone does not guarantee coverage.

Can a furnished or seasonal rental use the same coverage as a long-term lease?

Not necessarily. Describe booking duration, owner use, furnishings, management and occupancy gaps. The agency must review the actual rental arrangement and available policy terms before recommending an appropriate market.

What should an owner disclose about student tenants?

Describe the household and lease arrangement, including separate room leases, unrelated occupants and any owner-occupied portion. Identify owner-provided furnishings and tell the agency when the rental use changes.

Will rental-income protection pay when a tenant stops paying?

Ordinary nonpayment is different from eligible income interruption after a covered property loss. Review the covered cause, limits, repair period and exclusions in the actual contract. Separate wind or flood arrangements need their own review.

Which form should I use for several units?

Use the residential property form for one to four units. Use the apartment form for five or more units, including small multifamily buildings and larger apartment properties. Prepare a building schedule when the account includes multiple structures or locations.

Can I wait until a hurricane approaches to arrange protection?

Do not rely on last-minute binding. Carrier restrictions, TWIA moratorium rules, inspection requirements and flood waiting periods can affect timing. Confirm approval and effective dates for every contract before relying on coverage.

Do you have an office in the Coastal Bend?

Call 214-351-4097 or use the appropriate online quote form.

Tell us about your rental property

Choose the appropriate form. Insurance Plus serves owners throughout Texas: 214-351-4097.

Quote · 1–4 unitsQuote · 5+ units