Independent agency · Serving Texas since 1997214-351-4097
Insurance Plus
North Texas rental-property owners

Galveston Landlord Rental Property Insurance

Review Galveston landlord insurance quotes with accurate roof, occupancy and ownership records. A rental house and an apartment account can require different submissions. Insurance Plus can help compare available terms for the property you actually own.

An owner and property manager reviewing Galveston landlord insurance outside a rental home

Payment & billing options

Methods and installment plans vary by carrier. A quote request does not take payment or bind coverage.

Separate windstorm and flood before selecting a premium

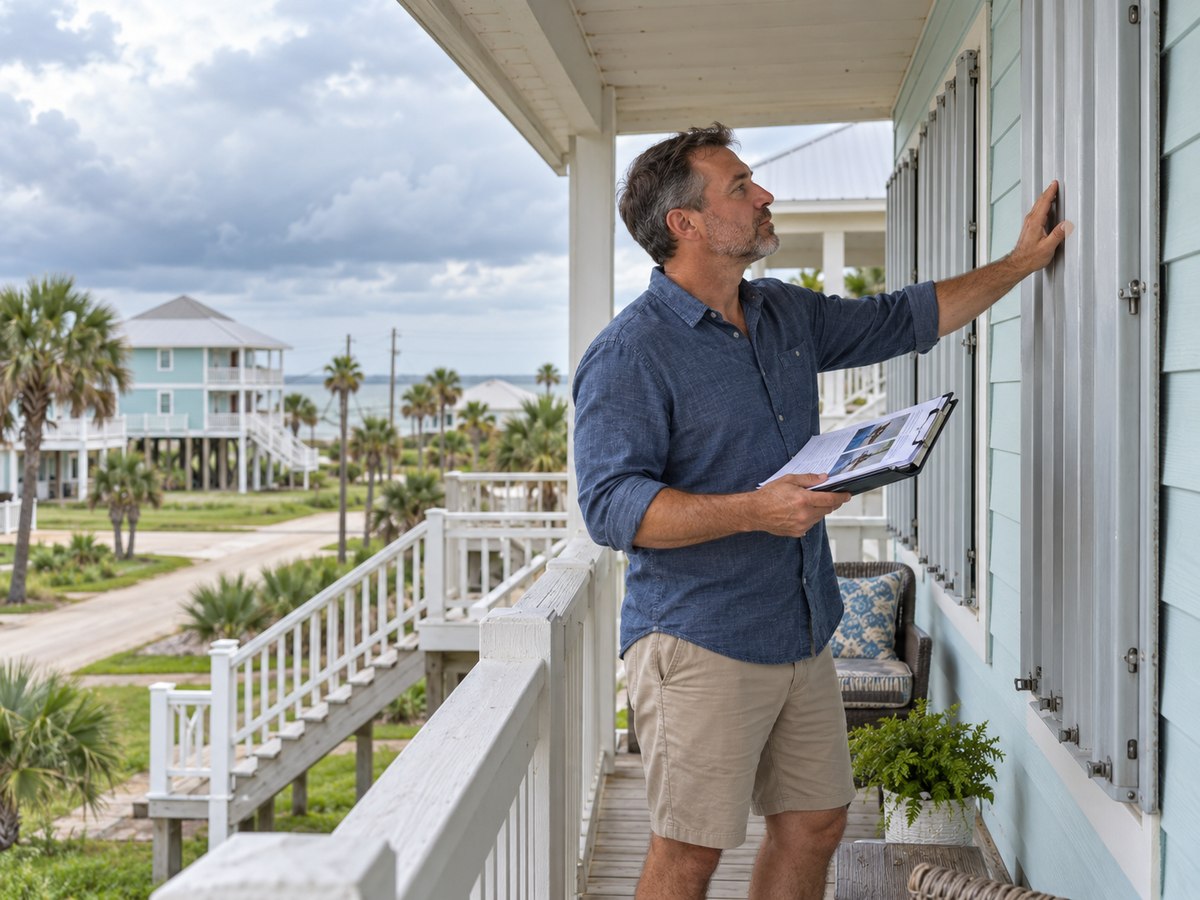
A property owner checking storm protection and roof records at a coastal rental

Wind, roof records and storm deductibles

For a raised island cottage, review the actual insured structure and the roof, stairs and other relevant building information. Do not assume the wind and flood contracts define every part of the property in the same way.

Galveston County coastal requirements can make construction and repair records important to a TWIA submission. Gather available certificates and explain later changes. Certification and underwriting acceptance remain different questions.

Compare hurricane or named-storm deductible triggers with roof settlement and any separate wind placement. Allow time for inspections and binding restrictions rather than rely on a last-minute change when a storm threatens.

Ask whether a percentage deductible uses the insured building value and how it applies to multiple structures. A share of insured value is different from a share of the repair bill.

Review wind-driven rain terms separately from the roof and flood discussions. Rain without a new opening, storm-surge water and plumbing discharge should not be assumed covered by the same provision.

Review windstorm options →
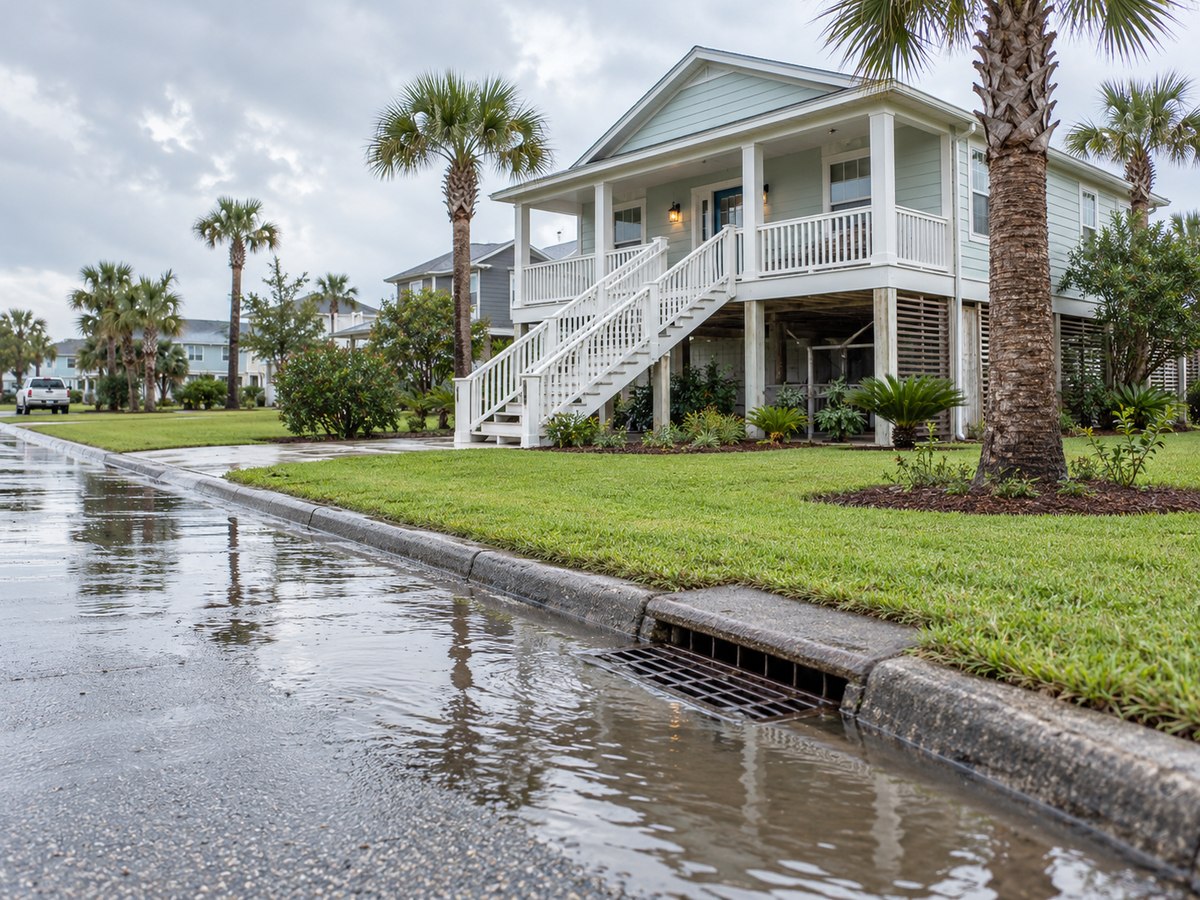
Rainwater along a street curb and drain near a coastal rental home

Rising water and separate flood terms

Review separate flood protection for rising water and storm-surge exposure. A windstorm policy is not a substitute for that review. Compare limits, deductibles, covered property and any waiting period rather than assuming the building and flood contracts are interchangeable.

Consider available mapping with the actual elevation, drainage and property history. A mapped boundary cannot establish the conditions at every building or guarantee that a property will not flood. Use official resources to ask informed questions about the address.

Wind-driven rain, rain entering a new roof opening, plumbing leaks and backup can be treated differently. Ask what the proposed forms actually cover and whether relevant endorsements are available. Do not treat a broad description of storm protection as a covered-cause guarantee.

If protection is split among contracts, identify which one includes eligible rental income and which event must make the rental unusable. An income limit under one policy does not establish the same benefit after a cause excluded by that contract.

Review flood protection →

Location, construction records and storm-season timing

Galveston County is in the designated coastal windstorm area. For a raised cottage or attached unit, review the actual insured structure and any association responsibilities rather than assuming wind and flood contracts describe the same property.

Where applicable, arrange required windstorm inspections before roof replacement or major work is concealed. TDI distinguishes qualifying ongoing-construction and completed-construction certificates. Exceptions depend on the project; a certificate is not a policy or guarantee of acceptance.

Review coverage early enough to resolve inspections, repairs and separate-contract dates. Carrier restrictions and TWIA moratorium rules can affect binding during specified hurricane conditions. A quote, payment request or closing deadline does not override those rules.

TDI inspection guidance →

Galveston rental property insurance for the building you own

A raised cottage, an attached coastal unit and a furnished vacation rental create different owner responsibilities. Describe the structure, stairs, enclosure areas and actual rental pattern. Do not submit seasonal or frequent guest use as a standard long-term household lease.

For Galveston rental property insurance, provide the building’s year, size, construction and actual unit arrangement. List ownership and mortgage interests rather than carrying forward a prior owner’s assumptions.

For an island property, evaluate the building, wind and flood arrangements as separate contracts where applicable. Compare insured property and rental-income terms rather than assuming storm-surge exposure is part of a wind policy. Association coverage also needs review for condominium ownership.

Keep the property description current through a purchase, repair or tenant change. Ask which inspection records and completed-work evidence the proposed market needs; an application should describe the premises as they stand today.

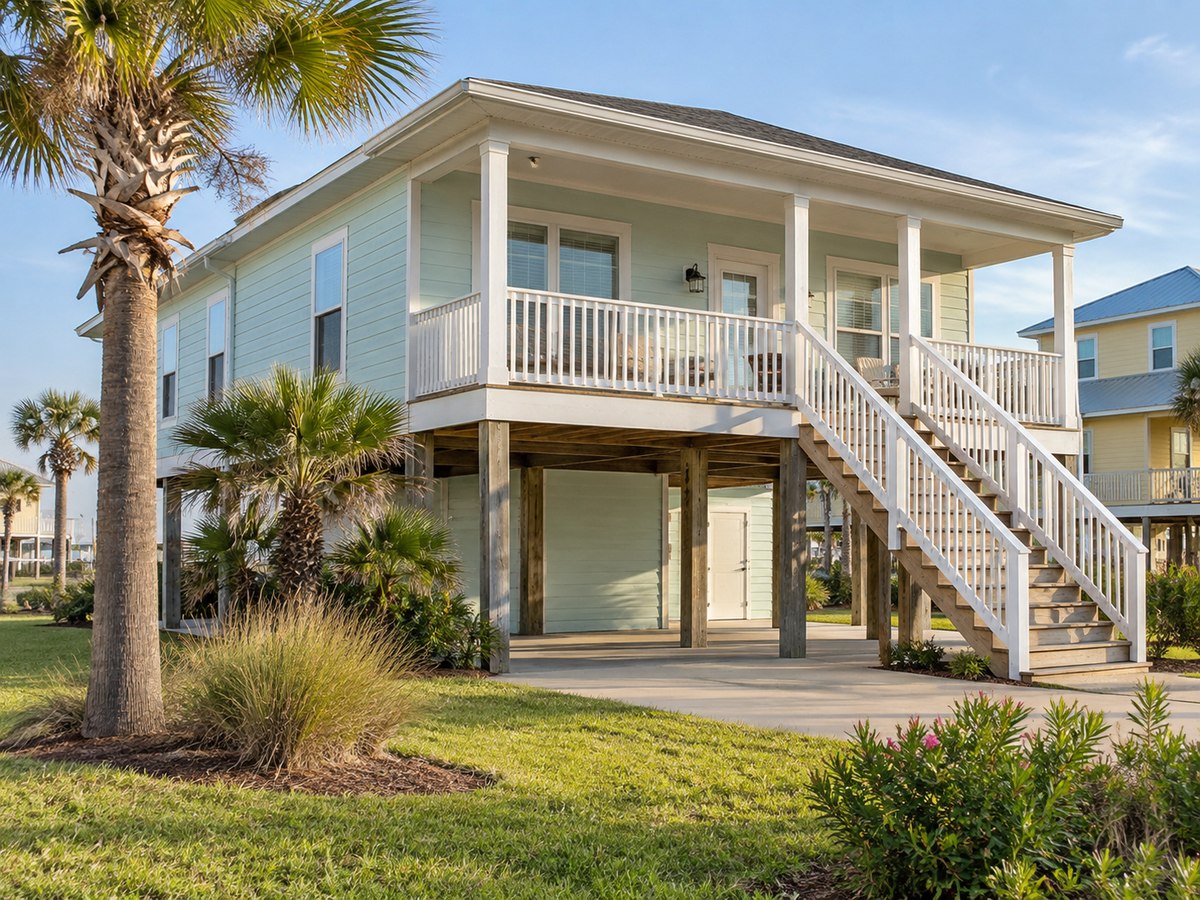
A maintained rental building illustrating Galveston rental property insurance considerations
Describe the actual structure and leased units. Property imagery is illustrative, not a specific listing.

Keep the rental arrangement and the maintenance records current

An owner recording furnishings in a rental living room

Seasonal rentals and the owner’s own use

Describe a vacation rental’s owner-use dates, typical guest stays and management. A house offered for frequent bookings is different from a long-term lease, even if both generate rental income.

Keep Galveston rental property insurance aligned with occupancy and ownership changes. Report the current arrangement before assuming the original terms remain appropriate.

Inventory furnishings and clarify who checks the property between stays. Explain unoccupied intervals, repairs and any retained personal space rather than presenting an uninterrupted household tenancy.

For an attached coastal unit, compare association responsibilities as well as the owner’s own contract. Platform protection does not automatically replace the building, furnishings and premises liability arrangements appropriate to the actual use.

An owner and contractor reviewing completed repairs in an empty rental home

Separate completed repairs from pending work

Keep turnover work organized by completed repairs, unresolved issues and future improvements. A fresh paint job does not establish the condition of plumbing, electrical systems or a roof. Provide records that explain the particular building rather than a generic maintenance summary.

If tenants leave after damage, explain the vacant period and the proposed repairs promptly. Utility disconnection, unoccupied units and structural work can change the market review. Waiting for renewal can leave the application describing a use that no longer exists.

Identify who is responsible for inspections, contractor access and emergency reports. Clear records help the owner answer questions, but routine care is still necessary. Insurance does not guarantee payment for deterioration or a project the owner intended to complete.

Read the vacant rental-property guide →

When comparing proposals, ask about any required inspections or repairs and whether relevant ordinance-or-law protection is available. Confirm outstanding items before relying on the proposed effective date.

Owner protection beyond the dwelling limit

Allow room for acquisition and renewal questions

Provide the closing or renewal date early, along with lender requirements and available inspection records. An urgent deadline does not establish that a market can accept the building or that pending repairs can be ignored.

Confirm approval, agreed terms, binding instructions, effective dates and any required payment. A form submission or preliminary premium is not a policy. Where a separate contract is needed, verify its own timing instead of assuming every part takes effect together.

Keep different water concerns separate

Flood, plumbing discharge, drain backup and rain entry can be governed by different provisions. Describe the concern and ask how the proposed wording treats it. A single water-related limit is not a reason to assume that every kind of water damage is insured.

Compare separate flood protection where appropriate, including the property insured and effective date. Ask which available endorsements address other relevant concerns. A building’s location and maintenance history support the discussion but do not guarantee a claim outcome.

Landlord insurance for Galveston rentals: review your options

Have building size, construction, roof material, update dates and current occupancy ready. Supply the address and ownership before comparing proposed limits.

Explain prior wind, water, fire or liability losses and the repairs completed afterward. Disclose a lapse or nonrenewal so the agency can review the current situation accurately.

Insurance Plus helps owners review Galveston landlord insurance for eligible residential rentals. Insurance Plus has served Texas since 1997 and can explain available proposals and required information.

Same-day markets are available for eligible rentals, subject to underwriting approval and binding requirements. A form requests a review; it does not issue a policy. Confirm approval, agreed terms, effective dates and required payment before relying on coverage.

An owner and insurance adviser reviewing building and ownership records at a desk
Organized building, occupancy and ownership records support a clearer proposal comparison.

Raised cottages and furnished guest use

Describe stairs, enclosed areas, storage and any separately occupied space in addition to the main living area. For an attached unit, obtain relevant association documents. Do not assume the building, wind and flood contracts insure identical portions of the premises.

If the owner uses the property personally or offers frequent guest stays, provide that pattern before selecting a market. Identify furnishings, turnover arrangements and periods without occupants. A long-term household rental description can leave important use details unanswered.

Compare any eligible rental-income benefit by covered cause and contract. Storm-related disruption alone does not establish a payment when the triggering loss or property falls outside the actual terms.

Nearby cities and communities

We also help rental-property owners in these nearby communities.

Texas City landlord insuranceView city coverage →
La MarqueService area
DickinsonService area
Jamaica BeachService area
HitchcockService area
League CityService area

Questions before choosing coverage

Does a flood map establish that an address cannot flood?

No. Mapping is one investigation tool, alongside the actual site, drainage and property history. Consider separate flood protection where appropriate; standard dwelling policies generally exclude flood.

What should I report before major repairs?

Explain current damage, vacant units, utilities, structural work, contractor access and expected completion. A proposal for an ordinarily occupied house should not be assumed suitable for an empty building under substantial renovation.

How should separately leased rooms be described?

Explain the household, room-lease arrangements, furnishings and any owner-occupied portion. Bedrooms and insured units are not interchangeable counts. Accurate current use is needed for market review.

Will ordinary unpaid rent qualify for an income claim?

Eligible rental-income protection generally concerns an interruption after covered property damage, subject to the contract. Ordinary nonpayment, eviction and routine turnover are different situations. Review the covered cause, limit and repair period.

What should I prepare when asking for assistance?

Call 214-351-4097 with the property’s current use, unit count and coverage questions. Keep the current declarations page and recent roof or repair records available for review.

Is same-day coverage available for every application?

Same-day markets are available for eligible rentals, subject to underwriting approval and binding requirements. A quote request does not itself issue coverage. Confirm agreed terms, effective dates and any required payment before relying on a policy.

Review the rental you own

Call 214-351-4097 or choose the appropriate quote form.

Quote · 1–4 unitsQuote · 5+ units