Independent agency · Serving Texas since 1997214-351-4097
Insurance Plus
North Texas rental-property owners

Longview Landlord Rental Property Insurance

For Longview landlord insurance quotes, describe the leased units, construction and current use before choosing coverage. Consider local property concerns and the contract’s conditions together. Insurance Plus serves rental owners statewide.

An owner and property manager reviewing Longview landlord insurance outside a rental home

Payment & billing options

Methods and installment plans vary by carrier. A quote request does not take payment or bind coverage.

Longview rental property insurance for the building you own

A house shaded by tall trees and a small duplex should be evaluated from actual roof, exterior and maintenance information. Explain detached structures, access and tenant responsibilities instead of assuming all property on the lot is insured the same way.

For Longview rental property insurance, provide the building’s year, size, construction and actual unit arrangement. List ownership and mortgage interests rather than carrying forward a prior owner’s assumptions.

For an older rental, separate completed electrical and plumbing updates from planned repairs. A sale inspection or an occupied lease does not establish that every issue has been resolved. Give the agency a realistic account of the building’s present condition.

A completed renovation and a planned improvement are different facts. Explain current roof and system condition, separate structures and any shared areas before comparing valuation and liability terms.

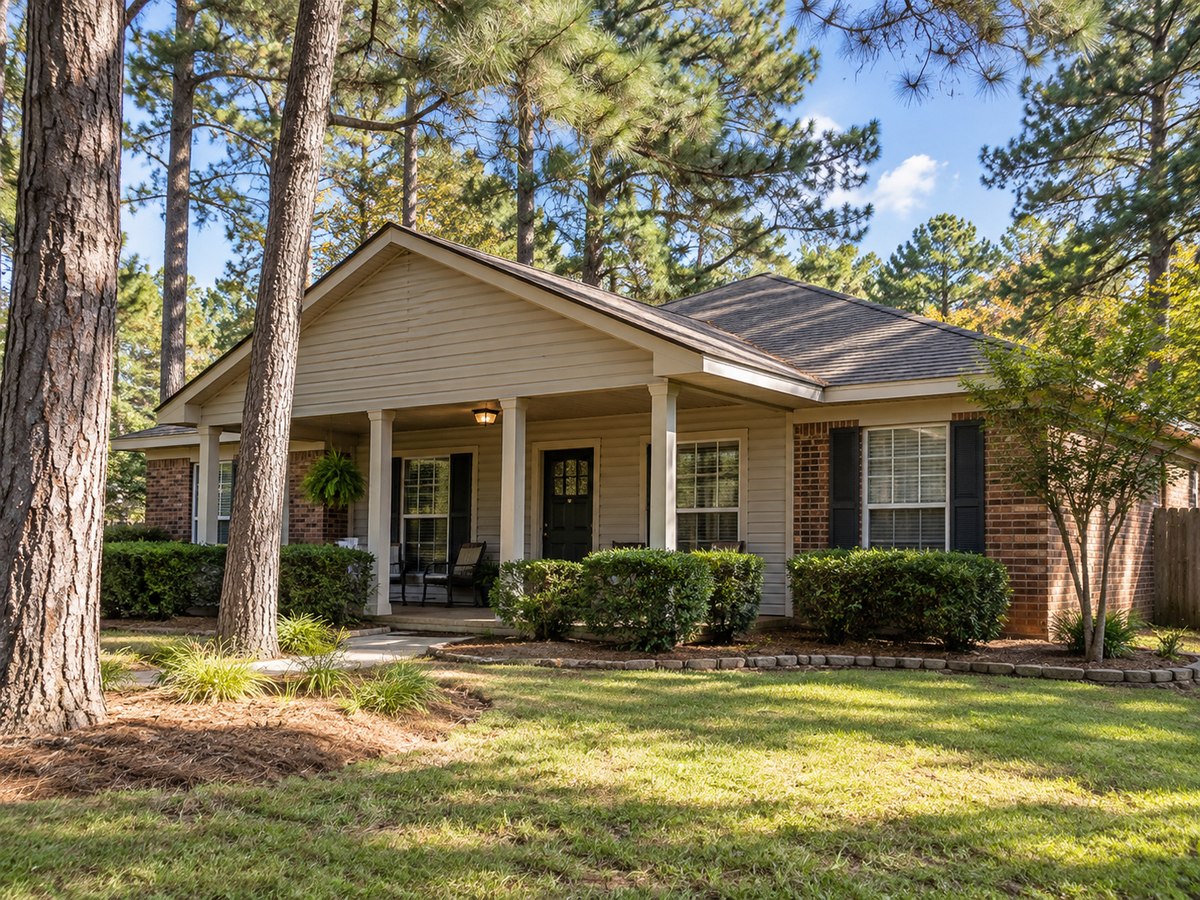
A maintained rental building illustrating Longview rental property insurance considerations
Describe the actual structure and leased units. Property imagery is illustrative, not a specific listing.

Exterior condition, storm records and water questions

For an East Texas rental beneath tall trees, keep roof and exterior-condition records with the maintenance history. Explain previous damage and actual repairs rather than assume the current yard’s appearance answers the building questions.

Ask how the proposed wording treats wind, falling objects and debris removal, including relevant limits. A storm nearby does not establish that every cleanup expense or damaged item is insured.

Longview’s floodplain information supplies another address-review tool. Tree shade and an older house do not establish water eligibility. Separate flood from pipe leaks, backup and rain entry, then compare the actual contract conditions.

An owner and contractor checking roof records and exterior condition from ground level
Illustrative property review; the photograph does not document a particular weather loss.

Use an official address resource

The local flood, drainage or weather resource can help organize questions about the premises. Check the specific site and available records; do not infer an individual property’s risk or eligibility from a citywide description. Mapping and prevention information do not replace the wording of a proposed insurance contract.

Keep the rental arrangement and the maintenance records current

A rental owner and manager reviewing occupancy and building records

Updates, ownership and reliable condition records

A house with a detached structure or separately used room needs a clear occupancy description. Identify utilities, access and any part retained by the owner before choosing the property category on an application.

Keep Longview rental property insurance aligned with occupancy and ownership changes. Report the current arrangement before assuming the original terms remain appropriate.

For an older building, distinguish completed electrical and plumbing updates from repairs recommended in a sale inspection. A recent tenant does not prove that every recommendation was resolved.

Keep the person responsible for maintenance and emergency reports identified. If repairs leave the property empty, report that condition rather than assume an occupied-house arrangement remains appropriate.
An owner and contractor reviewing completed repairs in an empty rental home

Inspection records through a change of tenants

A seller’s inspection, older invoice and current photograph can describe different stages of a building’s condition. Arrange the records by date so the review distinguishes a completed update from a recommendation that has not yet been carried out.

Disclose extended vacancy and renovations, including who controls the premises and whether utilities remain connected. A rental house between normal leases and an empty building with major work underway should not be submitted as the same exposure.

Keep the agency informed as work progresses or occupants change. If a contractor discovers additional damage, explain it instead of assuming the original application still describes the project. Read actual vacancy and renovation terms before relying on protection.

Read the vacant rental-property guide →

Review roof and major-system information with the repair schedule. Inspection requirements, settlement conditions and maintenance obligations are separate questions; meeting one does not establish automatic coverage for all damage.

Compare the terms that affect a covered loss

Review every address on an account

Organize building limits, roof dates, deductibles, occupancy, owner entities and mortgages by location. Include any separate contracts so the total premium does not hide a different restriction or uninsured cause at one property.

Locations may be reviewed together without qualifying for identical forms or carriers. Explain additional buildings and current tenants accurately. A new purchase, sale or vacancy should update the schedule rather than wait for the next annual comparison.

Separate the building from owner-owned items

List furnishings, appliances and maintenance equipment kept for the rental. Ask which limit addresses those items and which structures are insured separately. The dwelling amount should not be treated as proof that everything on the lot is covered.

Keep an inventory and photographs with your records, and update them when the owner replaces or adds property. Tenant belongings are generally a separate matter. Compare the actual described property and valuation rather than relying on one total on a declarations page.

Landlord insurance for Longview rentals: review your options

Collect the current declarations, building description and inspection findings. Identify every leased unit, separate structure and ownership interest on the submission.

Provide roof and major-system records with the loss history. Distinguish an open repair issue from completed work and tell the agency about vacancies, utilities or changed use.

Insurance Plus helps owners review Longview landlord insurance for eligible residential rentals. Insurance Plus has served Texas since 1997 and can explain available proposals and required information.

Same-day markets are available for eligible rentals, subject to underwriting approval and binding requirements. A form requests a review; it does not issue a policy. Confirm approval, agreed terms, effective dates and required payment before relying on coverage.

An owner and insurance adviser reviewing building and ownership records at a desk
Organized building, occupancy and ownership records support a clearer proposal comparison.

Tree-shaded buildings and documented repairs

An owner should distinguish routine exterior care from prior storm damage and completed repairs. Keep roof photographs, contractor invoices and inspection recommendations in date order. An attractive yard does not establish the condition of the building beneath it.

For a property with a detached garage or additional living area, describe the actual structures and tenant access. Ask about insured property and liability rather than assuming that every improvement follows the main building’s limit.

If updates or repairs leave the rental empty, report the expected duration and utility status. A plan to finish work before another lease is not evidence that the property is ordinarily occupied during construction.

Nearby cities and communities

We also help rental-property owners in these nearby communities.

White OakService area
GladewaterService area
HallsvilleService area
KilgoreService area
LakeportService area
Liberty CityService area

Questions before choosing coverage

What should I report before major repairs?

Explain current damage, vacant units, utilities, structural work, contractor access and expected completion. A proposal for an ordinarily occupied house should not be assumed suitable for an empty building under substantial renovation.

Does the purchase price establish the building limit?

No. Market value, the loan balance and reconstruction cost measure different things. Review an appropriate rebuilding estimate and the actual valuation and settlement provisions proposed for the structure.

Does an old homeowners description still fit after leasing the house?

Owner occupancy and tenant use are different arrangements. Tell the agency before a conversion so the appropriate program can be reviewed. A prior policy or declarations page is not evidence that a changed use has been accepted.

Are owner-provided appliances automatically included?

Do not assume they are. List the appliances, furnishings and equipment supplied with the rental and review the relevant insured-property limits, exclusions and valuation. Tenant belongings are a separate interest.

What should I prepare when asking for assistance?

Call 214-351-4097 with the property’s current use, unit count and coverage questions. Keep the current declarations page and recent roof or repair records available for review.

Is same-day coverage available for every application?

Same-day markets are available for eligible rentals, subject to underwriting approval and binding requirements. A quote request does not itself issue coverage. Confirm agreed terms, effective dates and any required payment before relying on a policy.

Review the rental you own

Call 214-351-4097 or choose the appropriate quote form.

Quote · 1–4 unitsQuote · 5+ units