Independent agency · Serving Texas since 1997214-351-4097
Insurance Plus
north Harris County rental-property owners

Spring Landlord Rental Property Insurance

Compare Spring landlord insurance quotes with roof, drainage and occupancy records available to the person managing the house. An off-site owner needs practical inspection access as well as suitable terms. Insurance Plus can help organize the property questions and review available coverage options.

An owner reviewing Spring landlord insurance with a property manager outside a rental home

Payment & billing options

Methods and installment plans vary by carrier. A quote request does not take payment or bind coverage.

Spring rental property insurance for the building you own

A pine-shaded house with a Spring mailing address should be reviewed from its actual location and management arrangement. County, watershed and building details matter more than a broad regional label.

For Spring rental property insurance, provide the building’s year, size, construction and actual unit arrangement. List ownership and mortgage interests rather than carrying forward a prior owner’s assumptions.

For an owner managing from another city, arrange access to roof, repair and occupancy records before seeking proposals. A detached guest space, owner-retained garage or furnished use needs explanation alongside the main rental.

Use an appropriate reconstruction estimate for building limits. The purchase price and loan balance are different measures. Identify detached structures, owner-owned appliances and furnishings so their limits can be considered separately.

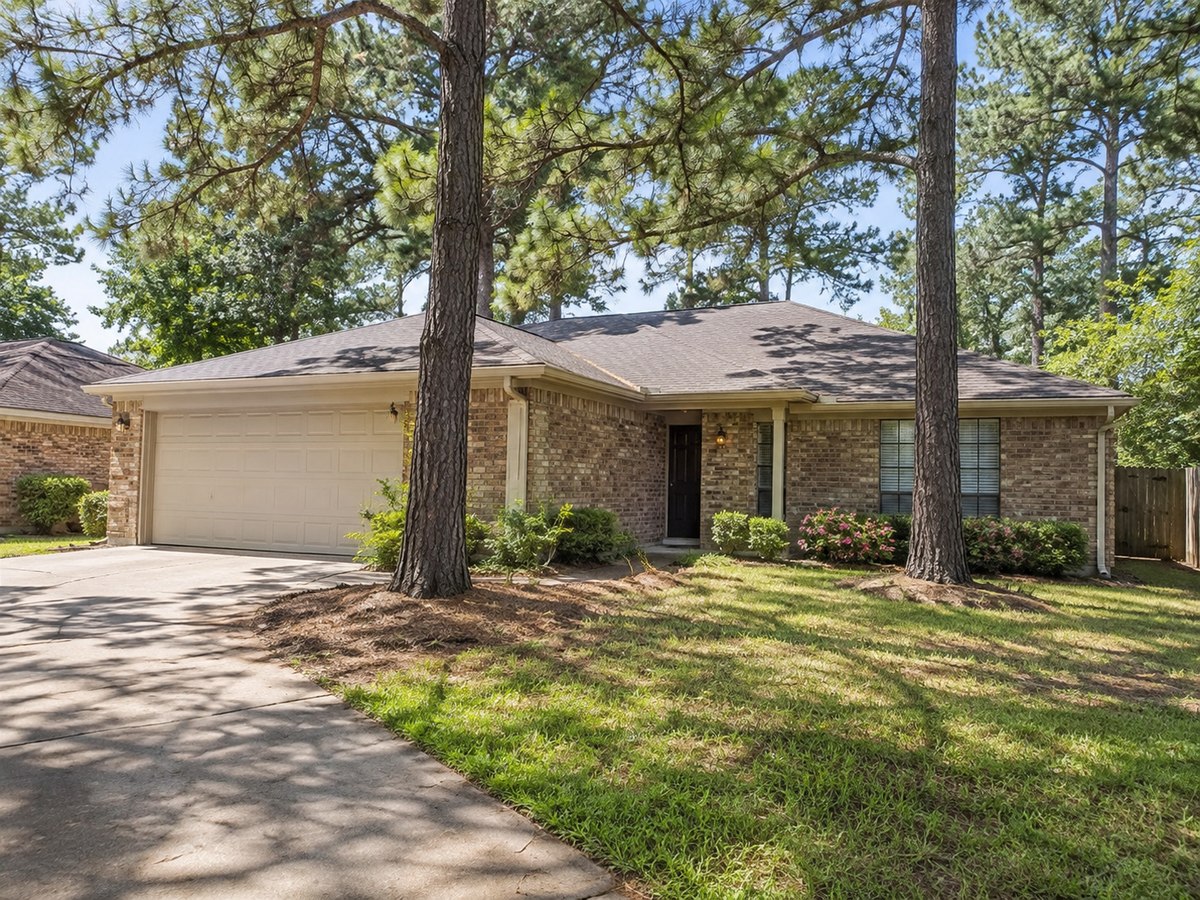
A maintained rental building illustrating Spring rental property insurance considerations
Describe the actual structure and leased units. Property imagery is illustrative, not a specific listing.

Keep the rental arrangement and the maintenance records current

An off-site owner reviewing property records with a local manager

Managing the rental from another location

An off-site owner needs a named person who can confirm current occupancy, meet an inspector and report storm damage. Clarify the practical arrangement without treating a management contract as automatic insurance protection for every participant.

Keep Spring rental property insurance aligned with occupancy and ownership changes. Report the current arrangement before assuming the original terms remain appropriate.

Keep records when tenants leave, utilities change or repairs become necessary. A house described as continuously occupied at application may need another review if it later sits empty or changes to furnished temporary stays.

List owner-owned appliances, furnishings and any stored property separately. Ask which structures and property limits apply when a garage or accessory space is kept for the owner rather than leased with the house.
An owner and contractor documenting completed repairs between tenants

Vacancy and work between leases

For an off-site owner, establish who checks the roof and drainage condition and can provide current photographs. Keep access and reporting contacts useful rather than relying solely on an old management agreement.

After severe weather, arrange safe documentation and report the facts through the proper channels. Retain temporary-repair receipts separately from permanent-work records. A repair estimate does not determine the covered cause.

Tell the agency when residents leave or repairs change the occupancy. Review eligible income benefits and vacancy conditions against the actual interruption rather than assuming every gap in rent is covered.

Read the vacant rental-property guide →

Ask whether ordinance-or-law protection is relevant when comparing covered repair terms. A planned remodel, code upgrade or vacant period should not be assumed insured merely because the building has a dwelling limit.

Review rising water independently of the building policy

Harris County Flood Control District provides Spring Creek watershed planning information. Use it to frame an address-specific drainage review, not as proof that a proposed improvement removes all flood exposure from nearby properties.

Wind-related roof damage and flood involve separate questions even during the same tropical weather event. Compare the roof’s settlement, deductible triggers and rain-entry terms independently of rising water and any backup option.

Do not apply the coastal windstorm designation to every Harris County rental. TDI limits it to specified areas east of Highway 146. A northern-county house may still need private-market wind and flood review without meeting that location rule.

A property manager checking gutters and ground drainage beneath tall pines
Illustrative property review; the photograph does not document a particular weather loss.

Use an official address resource

The local flood, drainage or weather resource can help organize questions about the premises. Check the specific site and available records; do not infer an individual property’s risk or eligibility from a citywide description. Mapping and prevention information do not replace the wording of a proposed insurance contract.

Review the insured interests behind the premium

Keep different water concerns separate

Flood, plumbing discharge, drain backup and rain entry can be governed by different provisions. Describe the concern and ask how the proposed wording treats it. A single water-related limit is not a reason to assume that every kind of water damage is insured.

Compare separate flood protection where appropriate, including the property insured and effective date. Ask which available endorsements address other relevant concerns. A building’s location and maintenance history support the discussion but do not guarantee a claim outcome.

Connect rent protection to covered damage

Eligible loss-of-rents coverage generally concerns income interrupted when covered property damage makes the rental unusable. It is different from an ordinary missed payment, eviction or the usual search for a new tenant.

Compare the triggering cause, dollar limit and covered repair period. Keep leases and rent records available. If building, wind and flood protection are split, identify which contract supplies any income benefit; a limit under one policy does not establish it under another.

Landlord insurance for Spring rentals: review your options

Prepare the address, year built, square footage, construction type, stories and unit count. Add roof dates, completed updates and the requested effective date.

Include prior losses, cancellations, nonrenewals, gaps and unresolved damage. Use actual records rather than guessing. A proposed effective date is not proof that outstanding conditions have been satisfied.

Insurance Plus helps owners review Spring landlord insurance for eligible residential rentals. Insurance Plus has served Texas since 1997 and can explain available proposals and required information.

Same-day markets are available for eligible rentals, subject to underwriting approval and binding requirements. A form requests a review; it does not issue a policy. Confirm approval, agreed terms, effective dates and required payment before relying on coverage.

A property owner comparing building records and proposed coverage with an agency representative
Organized building, occupancy and ownership records support a clearer proposal comparison.

A storm plan for an owner who lives elsewhere

Before severe weather, make sure the person responsible for access has the current policy contacts and knows which contracts cover the building, wind if separate, and flood if purchased. Keep copies available away from the premises.

If damage occurs, arrange safe documentation and report it through the appropriate channels. Record temporary work and receipts without assuming the first repair estimate establishes a covered cause or final settlement.

Tell the agency if occupants must leave or substantial work begins. Ask how any eligible income benefit and vacancy conditions apply to the actual circumstances instead of assuming all lost rent is reimbursable.

Nearby cities and communities

We also help rental-property owners in these nearby communities.

The Woodlands landlord insuranceView city coverage →
TomballService area
HumbleService area
Cypress landlord insuranceView city coverage →
ShenandoahService area
Oak Ridge NorthService area

Questions before choosing coverage

Does a watershed project guarantee the house cannot flood?

No. Planning information provides context for an address review. Investigate the actual site and relevant flood terms rather than treating a regional improvement as a property-level promise.

Does every Harris County house use coastal windstorm rules?

No. The TDI designation applies only to specified areas east of Highway 146. Review the particular location and private-market options; hurricane exposure alone does not establish TWIA eligibility.

Do records of repairs guarantee an offered policy?

No. Invoices, photographs and inspections help describe the current building, but eligibility, available forms and terms depend on underwriting. Explain remaining issues separately from work that has been completed.

Will ordinary unpaid rent qualify for an income claim?

Eligible rental-income protection generally concerns an interruption after covered property damage, subject to the contract. Ordinary nonpayment, eviction and routine turnover are different situations. Review the covered cause, limit and repair period.

What should I prepare when asking for assistance?

Call 214-351-4097 with the property’s current use, unit count and coverage questions. Keep the current declarations page and recent roof or repair records available for review.

Is same-day coverage available for every application?

Same-day markets are available for eligible rentals, subject to underwriting approval and binding requirements. A quote request does not itself issue coverage. Confirm agreed terms, effective dates and any required payment before relying on a policy.

Review the rental you own

Call 214-351-4097 or choose the appropriate quote form.

Quote · 1–4 unitsQuote · 5+ units