Dwelling Coverage
May help repair or rebuild the main home after a covered loss, subject to the policy limit, deductible, covered cause of loss, exclusions, and claim conditions.

We help property owners review coverage for the house, belongings, personal liability, other structures, deductibles, roof concerns, water losses, and local North Texas risks. Request a quote online or call our Texas agency for help.
Major credit cards and EFT/ACH may be accepted depending on provider eligibility, down payment rules, billing plan, and policy type.
Payment plans, escrow handling, mortgagee billing, and automatic payment choices vary by provider.
A policy is often requested because a lender needs evidence of insurance before closing, but the coverage should be reviewed for more than the mortgage requirement. A Lewisville home may need protection for the dwelling, detached structures, your personal belongings, personal liability, medical payments, and additional living expenses after a covered loss. The limits, deductibles, roof provisions, water limitations, and optional endorsements can matter just as much as the price.
Insurance Plus helps homeowners look beyond the basic proof requirement and think through how the property is used, how the home is built, what updates have been completed, and what local risks may affect the quote. The goal is to help match the property to the right available coverage route without confusing owner-occupied home coverage with condo, mobile home, vacant property, or landlord coverage.
Share the property details online or call Insurance Plus. We can help review what information may be needed before a quote can be completed.
Get a QuoteLocal agency support • Property coverage options
Your home's policy can include several coverage parts. Availability, limits, deductibles, endorsements, roof terms, and eligibility rules vary by property and provider. We help Lewisville homeowners review the major pieces so you get the right coverage for your needs.
May help repair or rebuild the main home after a covered loss, subject to the policy limit, deductible, covered cause of loss, exclusions, and claim conditions.
May help cover furniture, clothing, electronics, appliances, and other belongings damaged or stolen after a covered event, depending on policy terms.
May help respond to certain covered liability claims involving bodily injury or property damage to others, including defense costs where covered.
May apply to detached garages, fences, sheds, and similar structures on the residence premises, subject to the policy form and selected limit.
May help with additional living expenses if a covered loss makes the home temporarily unlivable and the policy conditions are satisfied.
Wind and hail deductibles, water backup, jewelry limits, equipment breakdown, roof settlement, and other details should be reviewed before choosing coverage.
Lewisville homes can face severe thunderstorms, hail, straight-line wind, roof wear, plumbing losses, foundation movement, mature-tree damage, liability exposure, and rising North Texas repair costs. Established neighborhoods may include older roofs and partially updated systems, while newer communities can have larger replacement values, complex rooflines, and higher-cost interior finishes. A quote that appears affordable may still contain roof, water, deductible, or coverage-limit details that deserve a closer review.
Lewisville includes established neighborhoods near Old Town, Timber Creek, Garden Ridge, and Valley Vista, newer development near Castle Hills and the Sam Rayburn Tollway, townhomes, condos, and properties near Lewisville Lake. Roof age, drainage, foundation history, nearby trees, detached structures, pools, solar panels, and renovation details can all affect the available coverage route.
Established and newer brick homes can have different roof, system, and rebuilding considerations.
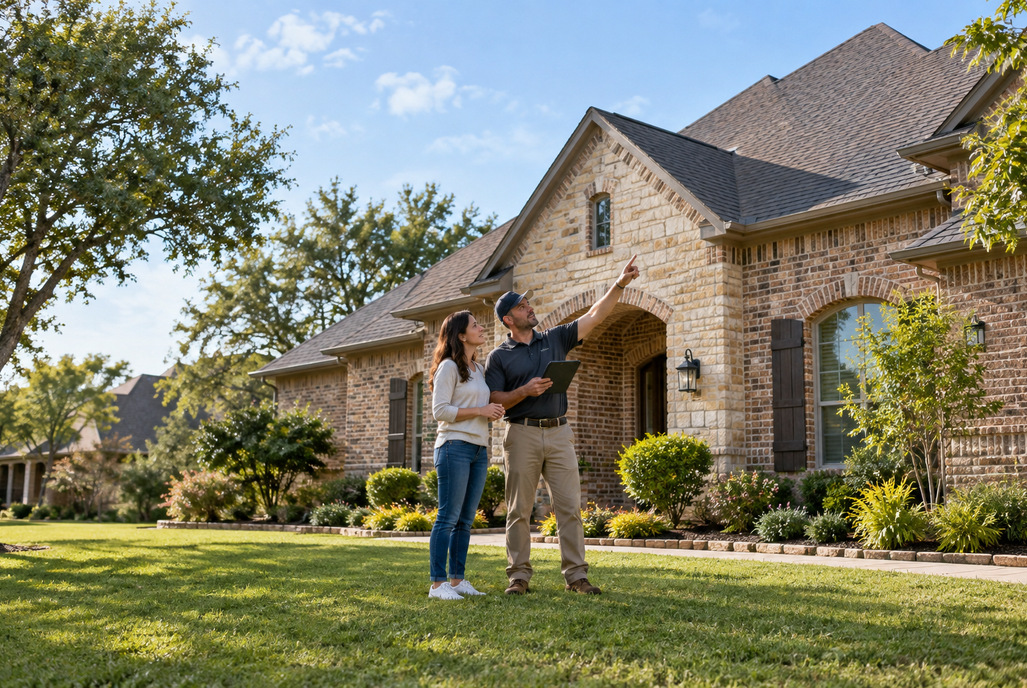
Roof age, storm history, materials, and settlement terms can materially affect a quote.
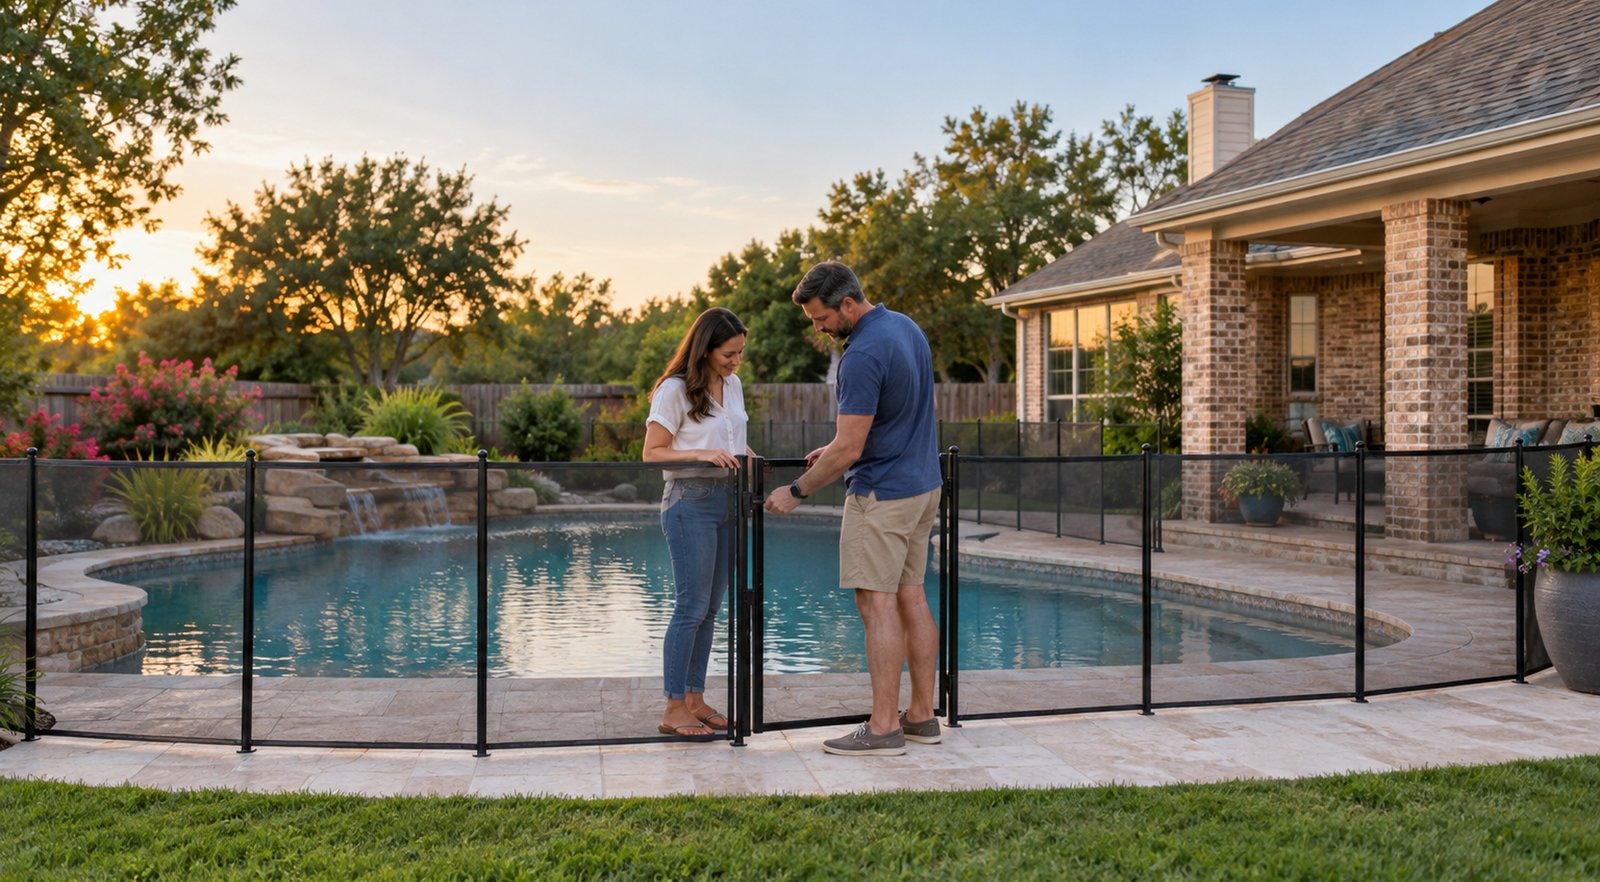
Pools, fences, detached structures, and outdoor living areas should be included in the coverage review.
For a home with several rounds of improvements, create a dated list rather than marking every system updated. Distinguish a repaired component from a full replacement. Include roof work, additions and detached structures, and explain any incomplete project. The construction date, improvement dates and present condition together give a more useful picture than any one answer alone.
Lewisville residences that look similar on paper may have very different improvement histories. Roof replacement, additions, pools, foundation repairs, updated mechanical systems, detached structures, and remodeling can materially change the present building, so those details are worth recording rather than relying on original construction data alone.
A Lewisville home may sell for one amount, appraise for another, and require a different amount to repair or rebuild after a covered loss. Market value can reflect land value, neighborhood demand, school district, location, and buyer activity. Replacement valuation focuses more on materials, labor, debris removal, local construction costs, and the features of the structure itself. That difference is one reason dwelling limits should not be chosen casually.
Compare the dwelling estimate with current floor area and finishes, then review limits for detached improvements. If a garage has become living space, explain the conversion. Check the proposal before assuming the original room count or reconstruction amount still represents the building.
The correct policy path depends on occupancy and property type. A home you live in, a condo, a manufactured home, a vacant house, and a rental property may all need different underwriting and coverage treatment.
A standard homeowners review usually begins with whether the house is owner occupied, regularly lived in, and used primarily as a residence.
Condo owners may need coverage for interior property, personal belongings, liability, loss assessment, and gaps in the association master policy.
Manufactured homes may require specialized review based on age, tie-downs, location, construction type, and provider eligibility guidelines.
A vacant home or home under renovation may not fit a normal homeowners policy and should be reviewed before assuming coverage applies.
Homes with prior claims, aging roofs, older systems, or unusual risk details may need a more focused high-risk home coverage review.
If the property is rented to tenants, visit our landlord insurance quote page instead of using an owner-occupied home quote path.
A set of current exterior photographs can also establish a practical baseline. Images of the roof, fences, trees, patios, drainage features, pools, and detached structures help document the condition and configuration of the Lewisville residence before a later weather event or inspection.
Our agency can help organize the gaps in a property record. If an invoice is unavailable, identify what you know and what remains unverified instead of supplying an estimated replacement year as a fact. Ask how the proposed terms address the roof, water losses and owner expenses. Keep lender instructions alongside those questions without treating them as a complete protection checklist.
Lewisville homeowners insurance should support your specific property and owner situation. A fast quote is helpful, but a clear quote is better when the details could affect claims, billing, mortgagee proof, or long-term satisfaction with the policy.
A change of ownership is a useful moment to reconcile inspection findings with the application. Note repairs promised after closing and confirm the expected occupancy date. For an owner remaining in place, use renewal to report material improvements or changes in use. In either case, obtain acceptance and the effective date before relying on a new contract.
Depending on provider eligibility, billing options may include a down payment, installment plan, mortgage escrow billing, EFT, ACH, or major credit card payment. Accepted payment methods and billing rules vary by provider, so they should be confirmed as part of the quote review rather than assumed.
A homeowner moving from renting to owning may care most about lender proof and affordability. A home in central Lewisville with mature trees and an older roof may raise different questions than a newer home in the newer neighborhoods of Lewisville, a townhome near a dense urban corridor, or a larger property with a pool. A homeowner with an older roof may need to focus on eligibility and roof settlement terms. A homeowner with recent remodeling may need to confirm whether the dwelling limit still reflects the updated structure.
The best quote conversation starts with the real situation. Is this a purchase, renewal, refinance, replacement policy, or urgent proof request? Is the house occupied now? Has the roof been replaced? Are there prior claims? Is the home titled as a condo, townhouse, manufactured home, or single-family residence? The answers can point the review in the right direction.
Homeowners often look closely at coverage only after a claim happens. It is better to review important details before a storm, fire, theft, water loss, or liability claim. Deductibles, roof settlement provisions, personal belongings, policy limits, jewelry sublimit, backup of sewer or drain endorsements, and loss-of-use limits can all affect how useful a policy feels at claim time.
For a Lewisville owner, separating major property changes from routine upkeep can make later reviews easier. Structural repairs, electrical or plumbing work, permanent additions, and substantial exterior improvements deserve dates and supporting records when available, while ordinary maintenance can remain part of the regular property file.
Roof condition and past storm repairs can shape questions during property review. Local agency support can be valuable when you need to explain a property situation, update mortgagee information, compare coverage paths, or understand why a particular home may require additional review.
As an independent agency, Insurance Plus can help review available options instead of limiting the conversation to one company path.
Keep prior inspection reports and repair invoices available when a carrier asks about property condition. Explain what work was actually completed.
We help separate homeowners, condo, mobile home, vacant home, and landlord needs so the quote starts in the right place.
Common questions from Lewisville property owners.
A homeowners policy may include coverage for the dwelling, other structures, personal property, liability, medical payments, and additional living expenses after a covered loss, subject to policy terms, deductibles, limits, and exclusions.
Roof age, material, visible condition, prior hail damage, wind exposure, and repair history may affect eligibility, pricing, deductible options, and available roof claim settlement terms.
Yes. Foundation movement, drainage, plumbing leaks, prior repairs, and unrepaired damage can affect underwriting. Flood and surface water generally require separate coverage from a standard homeowners policy.
A standard homeowners policy generally does not cover flood or surface water. Whether separate flood coverage is appropriate depends on the property location, flood zone, drainage, elevation, and lender requirements.
Not necessarily. A property rented to tenants or short-term guests may require landlord, dwelling, or specialty rental coverage rather than a standard owner-occupied homeowners policy.
Tell Insurance Plus about the property, desired effective date, lender needs, roof details, and coverage preferences. We can help review the available quote path.