
Dwelling Coverage
May help repair or rebuild the main home after a covered loss, subject to the policy limit, deductible, covered cause of loss, exclusions, and claim conditions.
We help property owners review coverage for the house, belongings, personal liability, other structures, deductibles, roof concerns for North Texas property risks. Request a quote online or call our Texas agency for help.
Major credit cards and EFT/ACH may be accepted depending on provider eligibility, down payment rules, billing plan, and policy type.
Payment plans, escrow handling, mortgagee billing, and automatic payment choices vary by provider.
A policy is often requested because a lender needs evidence of insurance before closing, but the coverage should be reviewed for more than the mortgage requirement. A Carrollton home may need protection for the dwelling, detached structures, your personal belongings, personal liability, medical payments, and additional living expenses after a covered loss. The limits, deductibles, roof provisions, water limitations, and optional endorsements can matter just as much as the price.
Carrollton’s large share of older housing makes system age an especially useful distinction. Original construction year alone cannot show whether a residence now has modern wiring, replaced plumbing, a newer roof, updated HVAC equipment, foundation repairs, or remodeled living areas. A concise chronology of those improvements can tell the property’s present story far better.

Share the property details online or call Insurance Plus. We can help review what information may be needed before a quote can be completed.
Get a QuoteLocal agency support • Property coverage options
Your home's policy can include several coverage parts. Availability, limits, deductibles, endorsements, roof terms, and eligibility rules vary by property and provider. We help Carrollton homeowners review the major pieces so you get the right coverage for your needs.
May help repair or rebuild the main home after a covered loss, subject to the policy limit, deductible, covered cause of loss, exclusions, and claim conditions.
May help cover furniture, clothing, electronics, appliances, and other belongings damaged or stolen after a covered event, depending on policy terms.
May help respond to certain covered liability claims involving bodily injury or property damage to others, including defense costs where covered.
May apply to detached garages, fences, sheds, and similar structures on the residence premises, subject to the policy form and selected limit.
May help with additional living expenses if a covered loss makes the home temporarily unlivable and the policy conditions are satisfied.
Wind and hail deductibles, water backup, jewelry limits, equipment breakdown, roof settlement, and other details should be reviewed before choosing coverage.
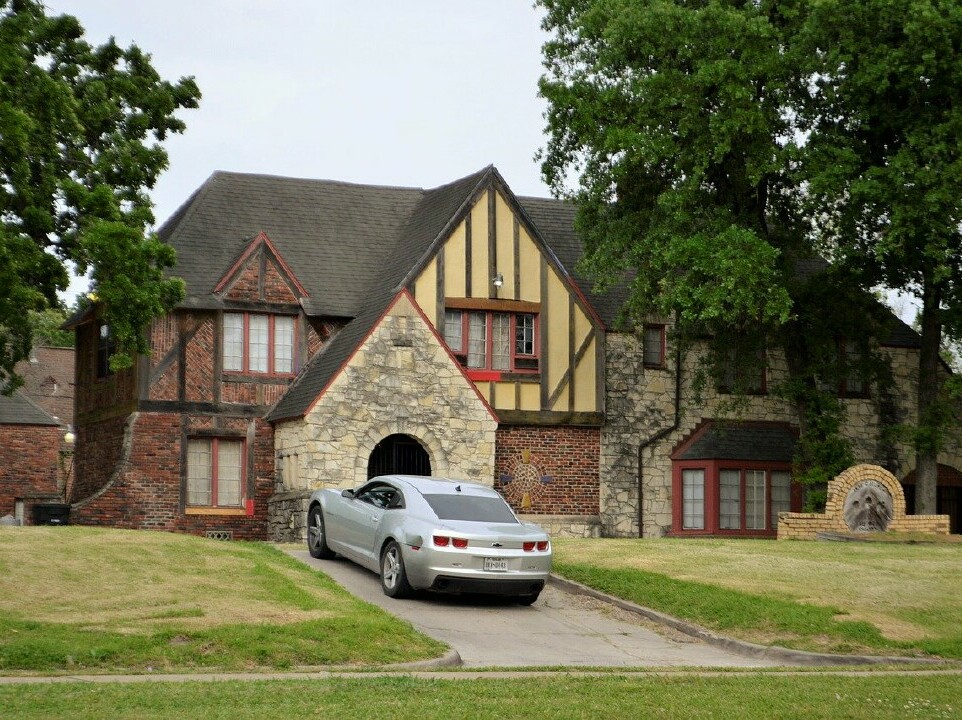
Carrollton’s residential stock has a meaningful older component. The city’s recent housing analysis reports that 64% of housing units were built before 1980. That makes the dates and scope of roof replacement, electrical work, plumbing updates, HVAC replacement, foundation repairs, additions, and other renovations especially useful when evaluating an individual property rather than relying only on its construction year.
The Dallas housing market also includes a wide range of property styles: traditional single-family homes, townhomes, historic homes, new infill construction, homes with detached garages, larger suburban-style properties, and residences with pools or other liability considerations. That variety makes it important to provide accurate details about the property instead of assuming every home can be quoted the same way.
Carrollton’s older housing component makes improvement history particularly important. Construction year may say little about a residence that has since received a roof replacement, foundation work, updated electrical service, new plumbing, modern HVAC equipment, windows, or an addition. Dates and documentation for those changes help establish whether an older property has been substantially modernized or still contains systems closer to their original condition.
Carrollton owners can reduce uncertainty by keeping records of major property work together. Foundation reports, plumbing invoices, roof warranties, permits, photographs, and remodeling contracts can explain changes that may not appear in basic property data. This is useful in a city where established neighborhoods contain houses of similar age but very different maintenance and renovation histories.
Carrollton spans portions of Dallas, Denton, and Collin counties, and market value can reflect many location-specific influences in addition to the structure itself. Reconstruction is a separate question. A renovated older residence with upgraded finishes and expanded living space may require different assumptions from a similarly priced property that remains closer to its original design.
Individual Carrollton residences can differ through foundation history, roof age, exterior construction, additions, garages, fences, pools, mature landscaping, and interior renovation. Those characteristics deserve direct review because two properties built in the same decade can now be very different buildings. The goal is to describe the residence that exists today rather than relying too heavily on age or neighborhood averages.
The correct policy path depends on occupancy and property type. A home you live in, a condo, a manufactured home, a vacant house, and a rental property may all need different underwriting and coverage treatment.
A standard homeowners review usually begins with whether the house is owner occupied, regularly lived in, and used primarily as a residence.
Condo owners may need coverage for interior property, personal belongings, liability, loss assessment, and gaps in the association master policy.
Manufactured homes may require specialized review based on age, tie-downs, location, construction type, and provider eligibility guidelines.
A vacant home or home under renovation may not fit a normal homeowners policy and should be reviewed before assuming coverage applies.
Homes with prior claims, aging roofs, older systems, or unusual risk details may need a more focused high-risk home coverage review.
If the property is rented to tenants, visit our landlord insurance quote page instead of using an owner-occupied home quote path.
Carrollton’s reinvestment programs also mean that some older properties have undergone major rehabilitation or replacement while others remain closer to their original form. Owners should distinguish structural work from cosmetic updating and record additions, rebuilt components, and major system replacements so the residence is evaluated on its current characteristics.
Our role is to help you think through the quote in practical terms: what is being insured, who occupies the home, what the lender may need, how deductibles work, whether the roof terms make sense, and whether optional coverage should be considered. We can also help identify when a property should be reviewed as a condo, mobile home, vacant property, higher-risk home, or landlord risk.
Carrollton homeowners insurance should support your specific property and owner situation. A fast quote is helpful, but a clear quote is better when the details could affect claims, billing, mortgagee proof, or long-term satisfaction with the policy.
Some homeowners need coverage because a closing date is approaching. Others are replacing an existing policy, responding to a nonrenewal, reviewing escrow changes, or checking whether a better option is available. When timing matters, it helps to gather the property address, owner information, mortgagee information, current policy details if available, roof age, past loss claims, and desired effective date before beginning the quote.
Depending on provider eligibility, billing options may include a down payment, installment plan, mortgage escrow billing, EFT, ACH, or major credit card payment. Accepted payment methods and billing rules vary by provider, so they should be confirmed as part of the quote review rather than assumed.
Carrollton also maintains five Neighborhood Empowerment Zones intended to encourage repair, rehabilitation, redevelopment, and qualifying single-family replacement. A residence in an established or reinvestment area may therefore have a very different improvement history from another house of similar age. Documentation of permitted work, rebuilt components, major systems, and structural changes can help make that distinction clear.
Foundation and plumbing documentation can be particularly valuable for an established Carrollton residence. Engineering reports, transfer warranties, repair invoices, leak corrections, and photographs help explain whether an issue was historical, repaired, or still active. Keeping those records with roof and renovation documents creates a practical property history for future reviews.
Waiting until claim time can make policy differences harder to sort out. Reviewing deductibles, roof settlement provisions, personal-belongings limits, jewelry sublimits, sewer-or-drain backup endorsements, and loss-of-use limits beforehand can make the coverage easier to understand when a storm, fire, theft, water loss, or liability event occurs.
A standard policy does not respond to every circumstance. Flood, earth movement, wear and tear, vacancy, business use, intentional acts, and maintenance problems may be excluded or restricted. Discussing those gaps before purchase can help determine whether separate protection or an endorsement is appropriate.
Insurance Plus serves Carrollton and other Texas property owners from its Dallas office. Agency support is especially useful when a property has unusual details, a lender needs updated mortgagee information, or an underwriting question requires more explanation before options can be compared.
Because Insurance Plus is independent, the agency can review available alternatives and discuss practical differences instead of presenting only one carrier's option.
Our Dallas office supports property owners who need quote help, policy guidance, payment information, or property coverage direction.
We help separate homeowners, condo, mobile home, vacant home, and landlord needs so the quote starts in the right place.
Common questions
A homeowners policy may include coverage for the dwelling, other structures, personal property, personal liability, medical payments, and additional living expenses after a covered loss, subject to policy terms, deductibles, limits, and exclusions.
Roof age, roof material, visible condition, prior hail damage, and repair history may affect eligibility, pricing, deductible options, and available roof claim settlement terms.
Yes. Condo and mobile home insurance may require separate review because coverage forms, property responsibilities, building details, and underwriting guidelines can differ from a standard owner-occupied house.
Rates can vary based on location, home age, roof age, construction type, square footage, claims history, coverage limits, deductible choices, selected endorsements, and provider eligibility rules.
No. A home you occupy and a property rented to others often need different coverage. Rental homes and investment properties may require landlord insurance rather than a standard homeowners policy.
Tell Insurance Plus about the property, desired effective date, lender needs, roof details, and coverage preferences. We can help review the available quote path.